Using multiple payment gateways means connecting your checkout and back office to several gateways, payment service providers (PSPs), or acquirers. Every new gateway or alternative payment method (APM) that isn’t already supported brings extra development, testing, and sometimes certification work.
Expanding to new regions or customer groups often requires new payment methods and providers. Adding each provider separately can become costly. Each launch is delayed by another integration, and the checkout experience can start to vary between payment methods.
Engineers have to work with a different API and software development kit (SDK) for each provider, while finance teams handle separate reports for each merchant account.
Common challenges include:
- Every new provider pushes back the launch. Each new gateway or APM adds its own round of development, testing, and certification.
- Checkout looks different for each payment method. Shoppers who run into an unfamiliar flow are more likely to drop off, which lowers conversion.
- Month-end close takes longer with every merchant account. Each account has its own reports, and finance has to reconcile them one by one.
- Maintenance grows with every connection. Ongoing updates for every provider and APM connection drive up maintenance costs.
Why Merchants Add More Than One Gateway
One gateway usually does not cover every market where a merchant sells. Merchants often add more providers for these reasons:
- Local payment methods. Customers in many markets expect local methods, such as Pix in Brazil, UPI (Unified Payments Interface) in India, or M-PESA in Kenya, and not every provider supports all of them.
- Coverage. A provider may not accept certain currencies, card types, or verticals, so some volume needs another route.
- Fallback. When one provider is down, payments can go to a second provider that supports the same payment method.
Lower processing costs and higher approval rates are the other common reasons. The business case for routing across several PSPs explains how merchants get them.
Ways to Integrate Multiple Payment Gateways
Merchants usually take one of four approaches: three connect several gateways, and one relies on a single provider that offers many payment methods and acquiring connections. The options differ in how much you build at the start and how much you keep maintaining as providers change their APIs.
| Approach | What you build | What you maintain as providers change | Adding a new gateway or payment method | Checkout and reporting |
|---|---|---|---|---|
| Direct integrations with each gateway | A separate integration for every gateway | Each provider’s API versions, SDKs and certificates | A new integration project for each new gateway, or for a method no connected gateway supports | A different flow and a separate report for each provider |
| One provider with many payment methods and acquiring connections | One integration with that provider | One API, within what that provider supports | Possible only if the provider already offers it | One flow and one report, limited to that provider |
| A payment orchestration platform | One integration with the orchestration layer | The platform maintains the provider connections | Enabled through the platform’s existing connectors, or a new one built on request | One flow and one report across providers |
| E-commerce platform plugins | A plugin installed and configured for each provider | Plugin updates and compatibility with your store platform | Depends on the plugins available and on how many providers your store platform lets you run at once | Limited to what the store platform and each plugin allow; a separate report for each provider |
With direct integrations, each new gateway goes through the same process, with credentials, sandbox access, build (including webhooks), testing, certification where the provider requires it, and, later, version upgrades. For what happens inside one gateway during a payment, see how a single gateway moves a payment from checkout to the bank.
Why Managing Several Gateways Is So Challenging
Each connector you add comes with its own integration, checkout flow, reports, onboarding checks, and maintenance, so the total effort grows with every new gateway.
Teams often underestimate the project and end up juggling several SDKs and dashboards. Launches slip, operations need more people, and customers notice that checkout behaves differently from one method to the next.
Technical Fragmentation
Every PSP or APM has its own API, SDK, release schedule, and error codes, and each new connector means learning them all over again. That extra work slows launches and adds to maintenance:
- Multiple SDKs add dependencies to track, update, and keep compatible with each other.
- Each provider’s API and SDK updates need their own upgrades and regression testing.
- Custom field mappings add data normalization work to every integration.
- Conflicting error codes make automated retry logic unreliable.
For the merchant, each market that needs a new provider waits for engineering capacity.
Managing Payment Methods Country by Country
Each market has its own range of payment methods, and handling that range from country to country is a separate task. Both before and after a launch, merchants need to keep track of:
- Methods per market. Which cards, wallets, bank transfers, and local methods customers in each country expect, such as iDEAL | Wero in the Netherlands, BLIK in Poland, or OXXO in Mexico.
- Provider coverage. Which acquirer or PSP covers which country and currency, and where the gaps are.
- Local rules. Strong Customer Authentication (SCA) in the EEA and the UK.
- Checkout setup. Which methods to enable or disable in each country, and in what order to show them at checkout.
- Reporting. Settlement and reconciliation by market and currency.
With direct integrations, each of these settings lives in a different provider portal. A change in one country, such as a new local method or a provider leaving the market, means configuration work across several systems.
UX Inconsistency
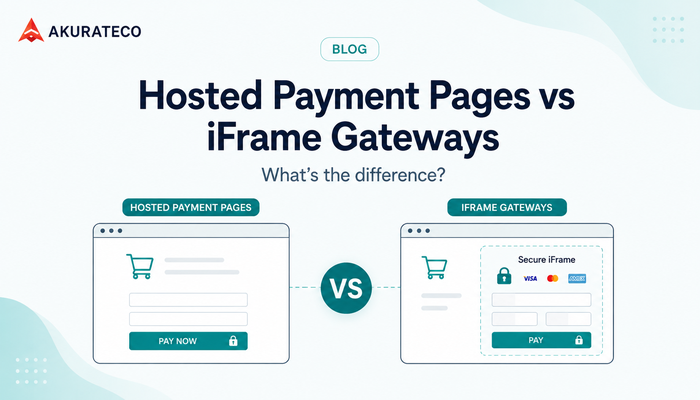
One provider sends customers to a hosted page, another uses an embedded form. If a customer switches from a card to a BNPL plan or a wallet, the flow can change halfway through, which damages trust. Since each provider has its own integration options, the checkout varies by provider and by country:
- When a redirect sends customers to a page that is hosted elsewhere, they leave your site, and some of them never return.
- Each provider’s SDK overlay has its own design, so the checkout no longer looks like your brand.
- 3‑D Secure works differently from provider to provider. Extra authentication steps appear, and approval rates can drop.
- A payment step that isn’t built for small screens loses more mobile shoppers.
For the merchant, that means orders lost at the very last step.
Reporting & Reconciliation Issues
Without a central hub, finance teams jump between merchant portals, CSV exports, and spreadsheets. With payments spread across providers, currencies, and time zones, the month-end close can take days longer:
- Figures from separate dashboards have to be merged by hand at every close.
- Providers format amounts and currencies differently, for example, decimal places or currency codes, and each mismatch can turn into a reconciliation error.
- Settlement reports arrive on different schedules, some of them late, so cash-flow planning often runs on incomplete data.
- Transaction logs sit in different systems, so a failed settlement can go unnoticed until someone chases a missing payout.
Compliance & Risk Management Overload
Each payment type and market requires its own compliance checks: for example, Payment Card Industry Data Security Standard (PCI DSS) for card data, PSD2 and SCA for payments in the EEA, and providers’ KYC/AML checks in each market.
Using different systems leads to inconsistent fraud control across payment types, which creates gaps and leaves teams rushing to adapt when regulations change. Here is what Akurateco’s team has seen in projects with several providers:
- Multiple rule engines multiply the compliance tasks the team runs each year.
- Misconfigured SCA triggers increase decline rates.
- Local KYC requirements add legal review for every new region.
- Fragmented logs complicate audit trails and lengthen audit preparation.
Each new region means compliance work for the merchant before they can take their first payment there.
Operational Maintenance Over Time
APIs change over time: parameters become outdated, certificates expire, and endpoint URLs are updated. Keeping several direct integrations running takes up DevOps time and increases maintenance costs for these reasons:
- Providers change their APIs on their own schedules, and some changes break existing integrations.
- If a certificate expires, payments can stop until it is renewed, so every renewal date must be tracked.
- Integration test failures rise after each provider update.
- When team members change, ongoing retraining is needed for each API’s migration process.
If You Run a Gateway on Top of Several PSPs
If you are a payment service provider or run a gateway, these problems increase with every merchant request and new market. Each new acquirer or payment method requires another integration, more certification, setup for each merchant, and ongoing maintenance.
Akurateco’s PSP clients have added methods and acquirers for their merchants in these projects:
- DineroPay, a licensed PSP in Saudi Arabia, added Apple Pay, Google Pay, and the BNPL options Tabby and Tamara to its platform with Akurateco.
- AzeriCard, an independent payment processing center in Azerbaijan, launched Apple Pay and Google Pay for card‑not‑present payments using network tokenization, with Akurateco handling the process from Apple’s and Google’s branding requirements to payment initiation.
- Platon, a Ukrainian PSP processing more than 3 million transactions per day, runs custom integrations with its acquiring banks on an on‑premises gateway deployed by Akurateco.
- TESS Payments, a PSP in Qatar, launched on Akurateco’s white‑label platform with a global connector (MPGS) and local connectors (NAPS and Doha Bank), with support through the Qatar Central Bank PSP license process.
What to Consider Before Expanding Your Payment Stack
Before adding new gateways or payment methods, review your team’s capacity and long-term goals. To avoid many of the challenges mentioned above, consider these questions:
How many new payment methods will you add in the next 12 months?
Each new connector requires its own development, testing, and certification time. If you plan to add several providers, make sure you have enough engineering resources available.
Are you selling in multiple regions or markets?
Expanding into regions like LATAM or MENA comes with specific compliance requirements and local payment preferences. Teams that plan each market’s methods and providers early can avoid doing custom work multiple times.
Do you have the development bandwidth to support ongoing maintenance?
Several gateways need constant updates: SDK version changes, API deprecations, new fraud rules. Without orchestration, maintenance costs keep climbing as engineers chase breaking changes.
Can you track each method’s performance in a single view?
When each payment provider has its own portal, it is easy to miss a spike in declines or fraud. With a single reporting layer, you can see approval rates, dispute volumes, and error codes for all providers in one place.
Have you defined your ideal checkout path?
Decide how you want the checkout to work before starting development. If you design the architecture early, cards, wallets, and other methods can follow the same process, and you will not need to rewrite error handling, retries, or UI placement at the last minute.
Where Payment Orchestration Fits
A payment orchestration platform sits between your checkout and your providers. You connect to it once, and then manage all connectors and each country’s payment methods in one place instead of separately for each provider. For more details, see how an orchestration layer works behind the checkout.
New cards, wallets, BNPL options, and local APMs then go through that same API. The main features of a payment orchestration platform:
- One API for Payment Methods: A single integration covers cards, digital wallets, BNPL, and local APMs available through connected providers, removing the need for a separate SDK per provider.
- Built‑in Routing Logic for Method‑Level Failover: Smart payment routing detects eligible failures, such as technical errors and soft declines, and reroutes transactions to a backup provider that supports the same method.
- Combined Monitoring and Reporting: A single dashboard tracks transactions, declines, and error codes across all methods, so there is no separate tool for each provider.
- Consistent UX Across All Methods: Cards, wallets, and BNPL share the same checkout flow, instead of each method displaying its own form layout and validation stages.
- Centralized Tokenization and Fraud Control: Tokenization keeps card data off your systems and reduces your PCI DSS scope, while 3‑D Secure for cards and fraud rules are managed in one place, which can simplify audits.
Provider API changes are handled by the orchestration layer, so developers do not need to respond to every update themselves.
Akurateco provides the gateway and orchestration layer on top of acquirers and does not process transactions itself. The platform gives access to 700+ integrations through one API; you can browse the list of available connectors.
The Final Word
Managing multiple payment gateways should not burden your team with technical debt, endless reconciliation, or constant development work. One gateway is easy to handle, but many connectors across different countries need a single layer to manage them. With an orchestration layer, each new provider connects through the same integration.
Wondering if your payment stack is ready to scale? Talk to our team for a readiness review.
FAQ
How do you manage payment methods across different countries?
Map each market first: the methods customers there expect, the acquirer or PSP that covers the country and its currency, and local rules such as Strong Customer Authentication (SCA) in the EEA and the UK. Then decide which methods appear at checkout in each country and in what order, and reconcile by market and currency. An orchestration layer keeps these settings in one place, not in each provider’s portal.
Can a merchant use multiple payment gateways at the same time?
Yes. Many merchants run two or more gateways in parallel, for example, one for domestic cards and another for a market or payment method the first one does not support. Some e-commerce platforms limit how many card providers can be active at once. Rules such as country, currency, or payment method decide which gateway handles each transaction. An orchestration layer manages all of them through one API.
Do I need a separate integration for each payment gateway?
With direct integrations, yes. Each gateway usually has its own API, credentials, and webhooks, and some providers also require certification. Each integration may also need updating when the provider changes its API. The main alternatives are e-commerce platform plugins, installed per provider; a single provider, if one covers all the methods you need; or a payment orchestration platform, where you integrate once, and the platform handles the provider connections.
What's the difference between adding a new payment method and optimizing existing ones?
Adding a payment method means building connectors, updating SDKs, and handling reconciliation logic for each provider. Optimizing existing methods means refining your routing, fraud rules, and retry policies inside one orchestration layer, with no new integrations required. The first is a project with its own timeline; the second is ongoing tuning of what is already live.
How do payment method choices impact checkout conversion in different regions?
Shoppers are more likely to finish a purchase when they see a payment method they already use, such as Pix in Brazil or a local e-wallet in much of Southeast Asia. A card-only checkout loses some of those buyers at the last step. Adding BNPL and wallets next to cards gives each market what it expects, and conversion holds up best when every option looks and works the same way.
Do orchestration platforms replace PSPs or work alongside them?
They work alongside them. An orchestration platform sits on top of the PSPs you already use and doesn’t process payments itself, so your existing contracts stay in place. Through one API, you connect all your providers and set rules for which one handles each transaction. Reporting from every merchant account then shows up in one place.
How can I track which payment methods are underperforming without switching PSPs?
A single dashboard shows approval rates, decline codes, and settlement times for every provider, so you can change a routing rule or move traffic to a backup provider without new integration work. To find the cause, split the same numbers by country and channel. If a method struggles with one provider but not the others, the problem is the provider. If it struggles everywhere, it’s the method.
Can we prioritize payment methods by channel (mobile vs desktop vs in-app)?
Yes. An orchestration layer lets you set routing policies per channel: for example, wallets first in mobile apps, cards first on desktop, and BNPL offered at checkout. Your codebase stays the same, and the checkout looks and works consistently across channels.