Many payment service providers (PSPs) rely on in-house software that generally meets their requirements but falls short of modern technologies and integrations. This software, tailored specifically to their needs, has proven reliable over time, making PSPs reluctant to replace it even though the underlying infrastructure may be difficult or impossible to upgrade.
There is a way to address this challenge that doesn’t require switching to another system: a payment gateway extension. It connects to the PSP’s current software, so the PSP keeps its core functionality and adds the extension’s integrations and features.
In this article, Akurateco’s Founder and CTO, Andrew Riabchuk, explains what an extension is, which problems it solves for PSPs, what PSPs add through it, and the two ways PSPs and their merchants connect to it. In short, the PSP adds acquirers, payment methods and features without moving its merchants to a new platform.
What is a payment gateway extension?
A payment gateway extension is a connection between a PSP’s existing payment platform and an external payment gateway through an open Application Programming Interface (API). It gives the PSP access to the gateway’s integrated acquirers, payment providers and risk tools, so the PSP can offer more services to its merchants without rebuilding its core system.
Instead of integrating separately with each acquirer, payment provider and fraud service, the PSP maintains one connection to the extension. The PSP also keeps control: transactions either pass through its own system or are copied into it. The term describes a server-side connection between payment platforms, not an e-commerce checkout plugin or a browser extension.
7 main issues that a payment gateway extension addresses
Here are the challenges an extension can address, which PSPs should consider when evaluating this approach.
Lack of integrated payment methods
A gateway extension fills the gap when a PSP’s own system lacks integrated payment methods. If the PSP lacks the expertise, time or a dedicated team to develop new integrations, it can add payment options through a ready-to-use extension. The extension already has multiple banks and payment providers integrated via open API, and the PSP connects to them through the extension instead of building each integration in-house.
The PSP connects once, through the extension’s open API, and then adds acquiring banks, alternative payment methods and local gateways without waiting for development resources. New providers no longer hold up merchant onboarding.
Insufficient functionality
A gateway extension suits PSPs whose software relies on long-standing legacy code that makes it hard to adopt modern payment technologies. Such PSPs have three options:
- Develop a new system with modern technologies from scratch.
- Switch to a white-label payment gateway.
- Connect a gateway extension and use its functionality with their current system.
An extension also helps local and global PSPs that serve specific regions and business verticals. When they expand into new markets or verticals, their existing functionality may not meet the needs of those markets.
For example, consider a payment service provider whose system currently processes only traditional card transactions. To meet the growing demand for alternative payment methods like crypto payments, the PSP needs new functionality to support this payment flow, and building it in-house would take significant time and money. Instead, the PSP can connect a ready-to-use extension from another payment software provider via an open API and get the functionality and integrations it needs.
Shortage of payment expertise
When a payment service provider operates within a specific payment industry, it has the expertise to offer advanced services to its existing merchants. However, if the PSP decides to enter a new market it is unfamiliar with, it might lack the expertise and knowledge required to operate successfully there.
By adopting an extension, the PSP gains more than access to the software itself. It also gets the expertise of the vendor’s dedicated payment team.
With the support of the vendor’s specialists, the PSP can adapt to the requirements of the new market, implement the necessary features and get advice on the market’s regulatory and compliance requirements, while licensing obligations remain the PSP’s own. This shortens the PSP’s time to market in new regions and helps it support local payment preferences.
Limited control over payment flow
Many payment software providers hesitate to work with third-party software because they fear losing the ability to monitor transaction flow and manage merchants, integrated banks and payment providers on their own. A gateway extension does not take that ability away. The PSP connects to an external gateway that routes transactions to acquirers and payment providers, and these transactions also pass through the PSP’s system or are copied into it, so the PSP keeps full control over the transaction flow.
Poor system infrastructure
Many payment service providers currently operate on legacy software developed a decade or more ago, when microservice architecture, process virtualization and orchestration systems were not yet used. While these providers recognize the benefits of embedding modern payment technologies into their software, implementing them would require a complete system rewrite.
The extension runs on a scalable architecture, so the PSP does not have to rewrite its own system. If the PSP needs to host that system in its own cloud, Akurateco also offers an On-Premises deployment.
As a hypothetical example, consider a PSP that processes 100K transactions on its legacy software and plans to handle 1M. Its existing infrastructure cannot accommodate that volume.
In this scenario, the PSP can connect an extension and offload the main part of the transaction load to it. The extension handles the larger volume, and the PSP scales its operations without extensive infrastructure improvements or costly upgrades.
PCI DSS scope for Server-to-Server integration
Compliance with the Payment Card Industry Data Security Standard (PCI DSS) is essential for payment gateways to handle card data securely. PCI DSS also affects which type of integration merchants can have with payment gateways.
Some merchants specifically want Server-to-Server (S2S) integration, which means they handle card data and must comply with PCI DSS themselves. However, not all PSPs are equipped to help their merchants achieve PCI DSS compliance, and some do not offer S2S integration at all.
In such cases, a gateway extension lets the PSP offer S2S integration to the merchants who need it. The vendor’s payment team can also help those merchants with PCI DSS compliance.
Threats to transaction security
As infrastructure grows more complex, PSPs face more security challenges. With a gateway extension, transactions pass an additional fraud-screening layer: they go through the PSP’s system and through the extension’s anti-fraud engine and third-party risk-scoring providers. These checks flag potential threats and reduce fraud risk for the PSP.
Fraud monitoring, chargeback alerts and KYC providers are already connected on the extension side. Instead of integrating each tool separately, the PSP can route part of its traffic through the extension and use these services there.
What PSPs add through a gateway extension: 3 use cases
Beyond closing gaps in a legacy platform, PSPs use an extension to add specific capabilities for their merchants. Three examples:
Smart routing, cascading and retries
Without routing, cascading and retries, a PSP loses transactions that could have been approved, especially during provider outages or traffic peaks. With an extension, the PSP sets its own routing rules on the extension side without changing its core payment system. Each transaction goes to the acquirer most likely to approve it. If the first attempt is declined, cascading sends it to another provider automatically, and soft declines are retried. For the PSP’s merchants, this means a higher approval rate and fewer lost payments. The routing guide explains how routing rules, cascading and retries work together.
Network tokenization
Network tokens are issued by card schemes and replace the card number in stored credentials. Connecting directly to each scheme’s token service is a separate integration project for a PSP. With an extension, the PSP uses the network tokenization already available on the extension side. For the mechanics, see how network tokenization works.
Apple Pay, Google Pay and Samsung Pay decryption
Mobile wallet payments arrive encrypted, and decrypting them requires certificates and setup with each wallet provider. Instead of arranging this itself, the PSP routes wallet transactions through the extension, which decrypts the wallet payload and sends the transaction to the chosen acquirer. The PSP can then offer Apple Pay, Google Pay and Samsung Pay to its merchants and route these payments across several acquiring banks.
How PSPs and their merchants connect to a gateway extension
Payment service providers connect to the extension using an open API. The PSP sends transactions to the extension, which forwards them to the payment partners that process them.
Additionally, the extension platform can replicate the PSP’s existing partner structure, including payment providers, merchants and their hierarchies. Mirroring this hierarchy makes the transition to the new setup smoother.
For merchants, there are two connection options:
Merchants stay on the PSP’s current system
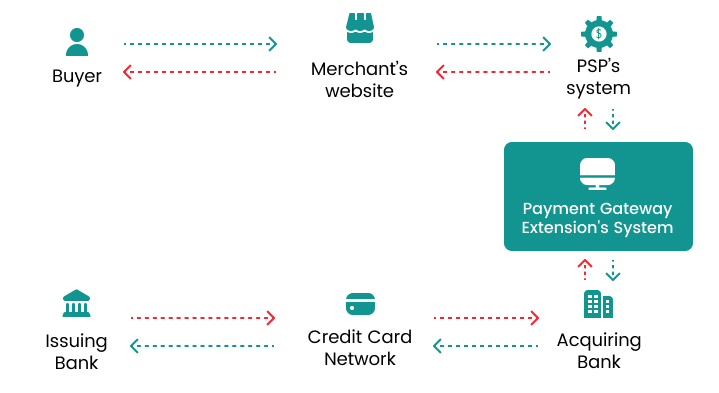
When merchants stay on the PSP’s current system, transactions flow through the PSP system and are then forwarded to the extension, which routes them to acquirers. Merchants keep their current dashboards, personal accounts and system interfaces and get access to the new integrations, payment flows and features the extension offers.
Merchants connect to the extension platform directly
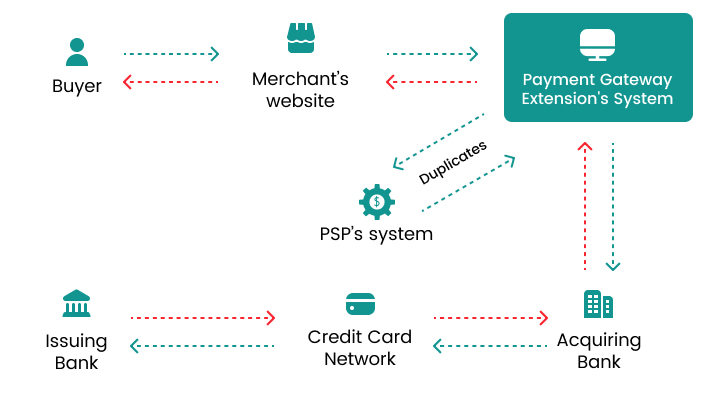
When a merchant connects to the extension directly, transactions go through the extension’s system first. They are still copied into the PSP system for monitoring and control. Merchants use the extension’s functionality directly, while the PSP keeps oversight of the payment flow.
Payment gateway extension from Akurateco
Akurateco provides the gateway and orchestration layer on top of acquirers and does not process transactions itself. Its extension gives PSPs 700+ integrations with banks and payment providers, smart routing with cascading and retries, connected fraud prevention and KYC tools, network tokenization, wallet decryption and Payment Team as a Service for setup and operations. See how Akurateco supports PSPs that upgrade an existing payment platform rather than launch a new one.
Contact us for a Free system Demo and a personalized consultation with our experts, and we’ll show how the extension would connect to your current platform.
Payment Gateway Extension FAQ
What is the difference between a payment gateway and a payment gateway extension?
With a standalone payment gateway, the PSP builds and maintains a direct connection to every acquirer, bank and payment provider. A payment gateway extension plugs into the PSP’s existing platform through one API and adds ready integrations, routing and risk tools; Akurateco’s extension adds 700+ integrations. The PSP keeps its own system and merchant base and expands what it offers.
Does a PSP lose control over its transactions when it uses a gateway extension?
No. Transactions either pass through the PSP’s own system before reaching the extension or, when merchants connect to the extension platform directly, are copied into the PSP’s system. The PSP keeps monitoring the transaction flow and managing its merchants, banks and payment providers, while the extension adds routing, integrations and risk tools.
How much development work does connecting a gateway extension take?
On the PSP side, the main work is one API connection to the extension. The extension can then replicate the PSP’s partner and merchant hierarchy, so the PSP does not set up its merchants and providers again from scratch. A typical connection takes 2 weeks, depending on how many providers and merchant integrations the PSP moves.
How can PSPs add payment methods for new markets without building each integration?
By connecting to a gateway extension that already has acquirers and local payment methods integrated. The PSP enables the methods it needs for each market instead of building a separate integration for every provider, so it can offer local payment options to its merchants without waiting for in-house development.