- What is an ISO/MSP? Meaning and differences
- Agent, unregistered ISO, or registered ISO/MSP: Which path fits you?
- How to become a registered ISO/MSP: step-by-step
- The sponsor bank relationship
- Visa and Mastercard registration: requirements and fees
- How much does it cost, and how long does it take?
- The ISO/MSP operating stack: software and payment gateway
- Why become a registered ISO/MSP? The economics
- Registered ISO/MSP checklist
- Conclusion
A registered ISO/MSP is a third-party company authorized to sell and support merchant payment processing services on behalf of a sponsoring acquiring bank. To register, you need that bank’s sponsorship and approval from Visa or Mastercard.
This article explains the steps to become a registered ISO/MSP, clarifies the differences between them, breaks down the costs, timeline, software stack, and gives recommendations to stand out in the crowded online payments market. You’ll also find a checklist for a quick overview of the required steps in a compact format.
What is an ISO/MSP? Meaning and differences
ISO/MSP both describe a third-party company registered to sell and support merchant payment-processing services on behalf of a sponsoring acquiring bank.
The distinction comes from each network’s own registration program. Visa registers its Independent Sales Organizations (ISOs) as one category of Third Party Agent (TPA) under its Third Party Agent (TPA) Registration Program, while Mastercard registers the equivalent role as a Member Service Provider (MSP) through the Mastercard Registration Program (MRP). ISO is much more frequently used than MSP, regardless of which network is involved.
Over time, most ISOs/MSPs began working across multiple acquiring banks and payment providers rather than sticking to just Visa or just Mastercard, and their role has broadened beyond simply connecting merchants to acquirers. Now, many bundle value-added services that make their offering more competitive.
It’s easy to confuse an ISO/MSP with a sales agent, but there’s a tiny clarification that distinguishes it. An agent works under an ISO/MSP’s registration and doesn’t hold one of its own, referring merchants for a smaller share of revenue.
A quick explanation of other adjacent terms:
- A processor handles the technical authorization and clearing of the transaction without itself settling funds or carrying merchant liability.
- An acquiring bank is the licensed entity that actually settles funds to the merchant and carries liability to the card networks (the relationship an ISO/MSP is registered to sell).
- A PSP (payment service provider) supplies the technology (a gateway, processing connections, and its own process for onboarding merchants onto its platform) that enables a business to accept payments and sell merchant services. A merchant onboarded this way typically becomes a sub-merchant under the PSP’s own account, rather than holding a merchant account in its own name.
- An ISO/MSP holds the card-network registration itself through a sponsor bank specifically to sell and support merchant relationships. Boarding a merchant here means registering it for its own dedicated account with that sponsor.
We explain ISO/MSP paths in more detail in the next section.
Agent, unregistered ISO, or registered ISO/MSP: Which path fits you?
All three paths come down to how much of the registration burden and merchant relationship you hold directly. You may not even need a full registration at all. Everything else, including costs, level of control, liability, and revenue, follows from the responsibility you’re ready to take on.
A quick comparison of the possible paths. Note that the costs below are typical ranges. It’s better to confirm current figures directly with your prospective sponsor before budgeting.
| Aspect compared | Sales agent under a program | Unregistered ISO under a registered one | Fully registered ISO/MSP |
|---|---|---|---|
| Upfront cost | Usually none, given that they work under someone else’s registration | Very low, as there are no heavy financial burdens from the card networks | Highest, with up to a $5,000 USD fee for registration per region confirmed for Visa, billed to your sponsor and typically passed through to you + $5,000 USD annual renewal (Mastercard’s isn’t publicly available), plus PCI DSS compliance, legal review, and possibly a bond or state registration, and technology/infrastructure used |
| Control | Lowest, as contracts sit with the sponsoring ISO or MSP | Moderate, includes ownership of the client portfolio (without recruiting sub-agents) | Highest, with the ability to hold merchant agreements directly and recruit sub-ISOs |
| Liability | Lowest too, as compliance risk sits with the registered sponsor | Moderate, since you’re working under the sponsor’s registration, but are accountable for the book you manage | Highest, as you’re directly accountable to Visa/Mastercard for every merchant you board |
| Revenue model | Smallest share (commission) | Residual share, which is larger than the sales agent’s; may also involve split arrangements | Largest share out of all three paths, with full margin, scalable by recruiting others, offset by the costs above |
Sales agent under a program
You work under someone else’s registration and connect merchants with ISOs, MSPs, or processors for a commission from a sponsoring ISO or MSP. No registration cost, no compliance burden, no direct merchant contract, thus getting a small cut of revenue.
Unregistered ISO under a registered one
A step up from the previous model. You still don’t hold your own registration, but the scope of control expands, and so does the revenue. You build and maintain your own book of merchant relationships while operating under a registered ISO/MSP’s card-network registration. It’s usually limited by your contract to subcontract or recruit your own sub-agents the way registered ISOs can. You work independently or for a larger registered partner, but you can’t scale by building a team beneath you.
Fully registered ISO/MSP
Full registration under your own name, sponsored by an acquiring bank. You hold merchant agreements directly, can recruit agents and sub-ISOs under you, and keep the largest share of the revenue. This model offers the highest level of control, so you’re paying much more upfront than in the two previous models.
Visa’s published fee for ISO registration is $5,000 USD for initial registration and $5,000 USD for annual renewal. Mastercard’s current registration fees aren’t publicly available, so any figure associated with Mastercard should be treated as an estimate until confirmed directly (checked in September 2026).
The actual price for a fully registered ISO/MSP needs confirmation with, first, a sponsoring bank and, second, the card network of your choice. Beyond that, take into account the budget for PCI DSS (Payment Card Industry Data Security Standard) compliance, sponsor/legal review costs, surety or fidelity bond, and technology question (build vs. license).
Starting as an agent? See our guide to becoming a payment processing agent for the next steps.
How to become a registered ISO/MSP: step-by-step
Every applicant works through a sponsor. It’s an acquiring bank that itself holds acquirer/card-network-member status, which vets your business, contracts with you, and submits your registration to the chosen network on your behalf. The exact requirements shift by region and by sponsor, but the sequence below covers the core steps, from setting up your business to launching as a registered partner.
1. Set up your ISO/MSP business entity
Choose a business structure, register it under your jurisdiction’s rules, obtain a tax ID and business bank account, and secure any local licenses or permits your services require.
This is entirely on you.
2. Build your business plan
Cover your target market, the services you’ll offer, your marketing approach, and financial projections. This is what you’ll present to prospective sponsors.
This is entirely on you.
3. Put AML, KYC, and PCI DSS programs in place
Draft anti-money-laundering and know-your-customer policies, and set a plan for PCI DSS validation if your ISO/MSP will store, process, or transmit cardholder data.
Not sponsor-dependent to build, but sponsors evaluate this directly.
4. Locate and evaluate prospective sponsors
Visa explicitly states that you can’t register directly. You must identify sponsors (acquiring banks that are themselves Visa and/or Mastercard members) willing to vet new entrants and compare their requirements and terms.
This is your own search.
5. Go through your sponsor’s due diligence review
Submit financial statements, legal formation documents, your business plan, and licenses; principals undergo background and credit checks.
Sponsor-dependent — the sponsor runs this review.
6. Sign your sponsor agreement
This finalizes revenue sharing, service levels, and compliance obligations between you and your sponsor (again, not with Visa or Mastercard directly).
Sponsor-dependent.
7. Let your sponsor submit your registration
Your sponsor forwards your documentation on your behalf.
Sponsor-dependent by design.
8. Complete the card network’s registration review
This includes underwriting, compliance verification by Visa or Mastercard, and payment of the registration fee (billed via your sponsor).
Depends on both your sponsor and the card network.
9. Complete training, integrate, and launch
Complete any compliance or fraud-prevention training your network or sponsor requires, connect your systems to your sponsor’s processing infrastructure, then launch. Ongoing from here: annual registration renewal and PCI DSS revalidation every 12 months.
Partly sponsor-dependent (system integration), partly card-network-driven (renewal, revalidation).
The sponsor bank relationship
Only an acquiring bank that is already a card network client can register an ISO/MSP. That’s a prerequisite for becoming a registered ISO/MSP. The sponsor reviews your business, signs the actual agreement with you, and forwards your registration to the card network. Without one, it’s impossible.
What a sponsor evaluates looks a lot like loan underwriting, because in effect, that’s what it is. The sponsor vouches for you to Visa or Mastercard with its own standing on the line. So, expect scrutiny of your financials, your compliance (AML, KYC, and PCI DSS readiness), background and credit checks on your principals, and your projected processing volume and merchant mix.
BIN sponsorship is the arrangement in which a licensed acquiring bank allows a third-party organization, such as an ISO, to process transactions on Visa or Mastercard under the bank’s own license and Bank Identification Number (BIN). ISO/MSP doesn’t hold separate network membership. The merchants you bring in run through your sponsor’s. That’s also why the sponsor bank stays ultimately responsible to the card networks for compliance and activity, even though the sponsored ISO handles much of the day-to-day merchant solicitation, boarding, and support.
ISOs find sponsors either by going directly to an acquiring bank that runs its own ISO sponsorship program or by going through a processor that itself holds acquirer status and offers sponsorship as part of signing up as one of its registered ISOs.
Visa and Mastercard registration: requirements and fees
Both need sponsors to register. The Visa’s ISO registration fee is $5,000 USD, covering initial registration. Annual renewal costs the same $5,000. But this cost isn’t final. Mastercard doesn’t publish a current, publicly accessible fee schedule for MSP registration.
The ongoing obligations for both networks, with some affecting the final cost:
- Annual registration renewal through your sponsor.
- PCI DSS revalidation every 12 months if you store, process, or transmit cardholder data. Visa’s own registry documentation confirms compliance must be revalidated annually.
- Correct use of each network’s marks and required registered-status disclosures, per that network’s brand guidelines.
You can find registries of compliance-validated service providers in both the Visa Global Registry of Service Providers and the Mastercard SDP Compliant Registered Service Provider List. If you see a company on the list, it means it’s registered and PCI-compliant. But not being listed doesn’t necessarily mean they aren’t, often because of timing or scope gaps. Confirming someone’s actual registration status is still best done by asking their sponsor directly.
How much does it cost, and how long does it take?
Costs break into three buckets: what you pay once, what you pay every year, and what it costs to actually run the business day to day. You can find only a few of these figures in public sources. The rest are negotiated individually, so treat them as budgeting placeholders until your sponsor gives you real numbers.
One-time costs
| Item | Cost |
|---|---|
| Business entity setup (formation, licenses, permits) | Varies by jurisdiction |
| Visa ISO registration fee | $5,000 USD |
| Mastercard MSP registration fee | Not publicly disclosed |
| Legal review of your sponsor agreement | Set by your attorney |
| Surety or fidelity bond, if your sponsor requires one | Set by your sponsor and bonding company |
Annual costs
| Item | Cost |
|---|---|
| Visa renewal | $5,000 USD |
| Mastercard renewal | Not publicly disclosed |
| PCI DSS revalidation, which includes QSA assessment (Level 1) or SAQ-D (lower levels) | Set by your QSA and scanning vendor |
| Liability insurance (optional but common) | Set by your insurer |
Operational costs
Staffing and technology are the two big variables here, and they scale with how you choose to run the business. Sales and compliance headcount costs vary by market and location. Technology carries long-term responsibility. Building your own processing infrastructure from scratch costs substantially more, in both money and time, than licensing a white-label payment gateway and building your ISO/MSP business on top of it.
Timeline
Neither Visa nor Mastercard publishes an official review time commitment, so treat these as realistic estimates to plan around, not as guarantees.
Entity formation and your business plan are self-paced. It takes days to a few weeks. Finding a sponsor and getting through their due diligence process commonly takes around 4 to 6 weeks once you’re actively engaged with one.
Give the card-network review several weeks on its own, and keep in mind that it can stretch further if your sponsor needs to go back to Visa or Mastercard for additional information, which is common enough in any underwriting-style review that it’s worth planning. That stage is largely out of your hands once submitted. The best way to keep it short is a clean, complete application the first time.
Adding those stages together, a clean application may realistically take two to four months from entity formation to the first transaction.
The ISO/MSP operating stack: software and payment gateway
Once you’re registered, running the business day to day comes down to a handful of core functions, and whatever platform you build or license is worth judging against how completely it covers them.
Start with merchant boarding and hierarchy. A registered ISO/MSP isn’t just onboarding individual merchants. If you recruit agents or sub-ISOs underneath you, you need to manage that structure as a hierarchy, not a flat list of disconnected accounts. This is one of the more concrete things to check in any platform to see whether it can onboard, configure, and monitor sub-merchants, sub-ISOs, and agents from a single system, or if you’ll be stitching several tools together to get the same view.
Routing sends each transaction to whichever provider offers the best trade-off between processing cost and approval odds. Cascading automatically retries a declined transaction (soft decline) through a different provider within the same attempt instead of losing the sale outright. The gap between a platform that does this and one that doesn’t shows up directly in your numbers.
Risk controls aren’t optional, and your sponsor and the card networks expect ongoing compliance, not a one-time check at registration. That means PCI DSS compliance appropriate to your service-provider level (Level 1 for the highest volumes), fraud filters, and risk-scoring built into day-to-day operations, plus tokenization, which replaces cardholder data with a non-sensitive reference token, so the original data isn’t stored in a form that becomes your liability.
Reporting and residual tracking go hand in hand, since your revenue is a share of the markup over interchange and service fees. Fee structures are different, so you need a way to set different rates per merchant or sub-ISO and automate the invoicing that follows. You also need visibility into payment data and analytics, including sales, payment trends, refunds, and chargebacks, to track what you’re actually owed, not reconstruct it at month-end from a processor’s raw statement.
Last but not least is portability. It’s how boxed in you are to a single relationship. A platform connected to a wide network of banks and payment providers rather than one acquirer means adding a new provider or entering a new region is a configuration change, not a fresh integration project. Akurateco’s platform, for instance, connects 700+ integrations through one API.
Building all of this in-house is possible. But it’s a long-term, expensive project layered on top of registration itself, which is why registered ISO/MSPs may want to license a white-label gateway rather than build one. It saves at least one year that you would spend on custom development alone. Ready-built platform capability is worth weighing as part of registration planning.
Why become a registered ISO/MSP? The economics
The core appeal is recurring revenue. As a registered ISO/MSP, you earn residuals. It’s a percentage of the transaction fees your merchants generate for as long as they keep processing, plus direct service fees that create income independent of volume.
If you hold a registered status, you can get the full revenue mix. It lets you hold merchant agreements directly, set your own pricing, and keep the full margin, without splitting it with whoever you’re operating under, the way an unregistered ISO or agent has to.
Beyond processing, revenue increasingly comes from what you sell alongside it. That’s actually the reason why expanding into branded payment software gives ISOs and MSPs a more comprehensive offering. The capabilities we covered in the operating stack above (routing, risk controls, analytics, and the rest) are what you can bundle, and reselling them under your own brand turns a commoditized processing relationship into a broader software relationship, and that’s its own revenue line. As a result, it attracts a larger merchant base, drives higher transaction volume, and opens up revenue streams beyond the core residual split.
Registered ISO/MSP checklist
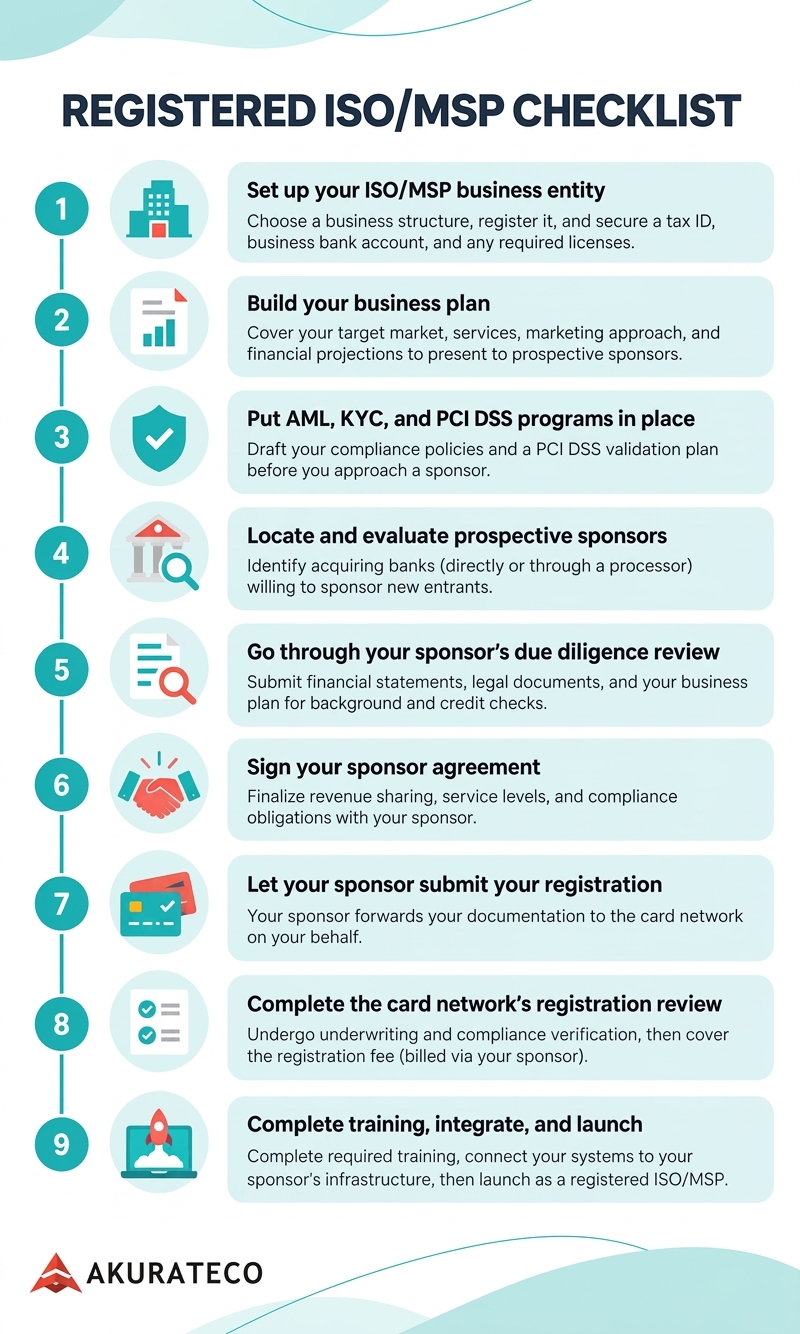
A quick-reference version of the steps. Save it to see exactly what’s required to become a registered ISO/MSP.
Conclusion
You can become a registered ISO/MSP with the help of a sponsoring acquiring bank. Applying directly to Visa or Mastercard isn’t possible. Compared to an agent or unregistered ISO, this model gives you full control, greater liability, more revenue potential, and also higher setup costs. From there, the technology you run on, built in-house or licensed, determines how much of that potential you can actually turn into revenue.
If you are looking for a reliable financial technology partner, take a look at Akurateco, a white-label payment gateway provider with 700+ integrations and advanced payment technologies in a single platform.
Registered ISO/MSP FAQs
What is an independent sales organization?
An independent sales organization, shortened to ISO, is Visa’s term for a third-party company registered to sell and support merchant payment-processing services on behalf of a sponsoring acquiring bank. Mastercard’s equivalent term for the same role is MSP.
What does “registered ISO of a bank” mean?
This is the disclosure you’ll typically see in an ISO’s website footer or marketing materials. It means the ISO’s registration is backed by a specific sponsoring bank, which has vetted the business, signed the agreement, and submitted the registration to Visa or Mastercard.
How much does ISO registration cost?
Visa’s published fee is $5,000 for initial registration and $5,000 annually to renew it, confirmed directly from Visa’s own Third Party Agent Registration Program documentation. Mastercard doesn’t publish an equivalent fee schedule, so that figure should be confirmed with a sponsor rather than assumed. PCI DSS compliance, legal review, and technology costs add to the total.
How long does it take to become a registered ISO?
Neither Visa nor Mastercard publishes an official timeline, so any figure is an estimate based on typical sponsor and processor experience. A realistic range is two to four months from forming your business to processing your first transaction, with sponsor due diligence and card-network review being the two stages most likely to extend that timeline.
Does an ISO need a sponsor bank?
Yes. Visa explicitly states that third-party agents (Visa’s umbrella term, which includes ISOs) can’t register directly with the network. Registration is only possible through a sponsor. That sponsor must be an acquiring bank that already has card-network-member status.
What is the difference between an ISO and an MSP?
The difference in names comes from each network’s own registration program. ISO is one type of registered agent under Visa’s Third Party Agent (TPA) Registration Program. MSP is the equivalent role registered through the Mastercard Registration Program (MRP). ISO remains the far more commonly used term, regardless of which network is actually involved.