Before a merchant can accept online payments, a payment provider has to onboard it. Merchant onboarding verifies the merchant and aims to let it accept payments for goods and services as quickly as possible. The procedure is familiar to every PSP and acquirer, but the way it is organized affects how quickly new merchants start processing.
This guide explains what merchant onboarding is, how the process works, which documents merchants usually need to provide, and how KYC, KYB, AML, and PCI DSS checks fit into the onboarding workflow.
What is the merchant onboarding process?
Merchant onboarding is the process through which PSPs, acquirers and other payment providers verify merchants and set them up to accept payments. It refers to the series of actions taken to register a merchant with a payment processor or acquirer.
When a merchant wants to accept payments for goods and services online through a particular payment provider, the provider runs an onboarding process to confirm the merchant is trustworthy and eligible to receive payments.
Manual vs automated merchant onboarding
There are two ways payment service providers (PSPs) and other fintech solutions handle onboarding – manually or automatically. As you scale and the number of merchants you work with grows, choosing between manual and automated onboarding becomes increasingly important.
Below, we break down the challenges of manual onboarding and explain what automation changes for your team and your merchants.
The pitfalls of manual onboarding
There are several things you should take into account when onboarding merchants manually:
- Operational bottlenecks and resource strain.
Manual onboarding requires your merchants to send documents one by one to an account manager. As onboarding requests increase, your team either needs to scale, which is costly, or face delays that slow down operations and increase overhead.
- Slow approvals and poor merchant experience
High workloads, time zone differences, and limited availability often result in long wait times before merchants can start accepting payments. These delays harm the first impression and may cause merchants to lose confidence in your service early on.
- Scattered communication and disorganized data
With files shared across emails and messengers, onboarding data becomes fragmented. Your team must manually collect and input everything into your system, a process that’s inefficient and prone to errors, especially when dealing with multiple merchants at once.
What is automated merchant onboarding?
Automated onboarding lets merchants fill in application forms and upload all required documents directly within your platform, at their own pace. This cuts down on back-and-forth communication and shortens the process, so merchants start accepting payments faster. It is particularly useful for PSPs, payment platforms, acquirers, and ISOs/MSPs that are scaling merchant acquisition and need to handle growing application volumes.
Here’s how it helps payment service providers:
- Merchants onboard themselves
With automation, merchants can begin the process directly from your website and follow step-by-step instructions without waiting for a representative. In many automated onboarding systems, merchants can also access documentation, track progress, and complete technical setup steps without waiting for every action to be handled manually.
- Operational efficiency for PSPs
Your team’s role shifts from performing manual tasks to monitoring merchant progress, reviewing submitted data, and supporting where needed. With automation, a task that used to require a dedicated team of three can now be handled by one employee. Notifications help your team stay updated on merchant status without constant follow-up.
- All data in one place
Automated platforms consolidate all onboarding information into one centralized merchant record, so the required data is accessible in one place.
- Customization and scalability
Advanced systems also allow PSPs to tailor onboarding forms to the merchant’s country of incorporation, business model, risk profile, or required compliance checks.
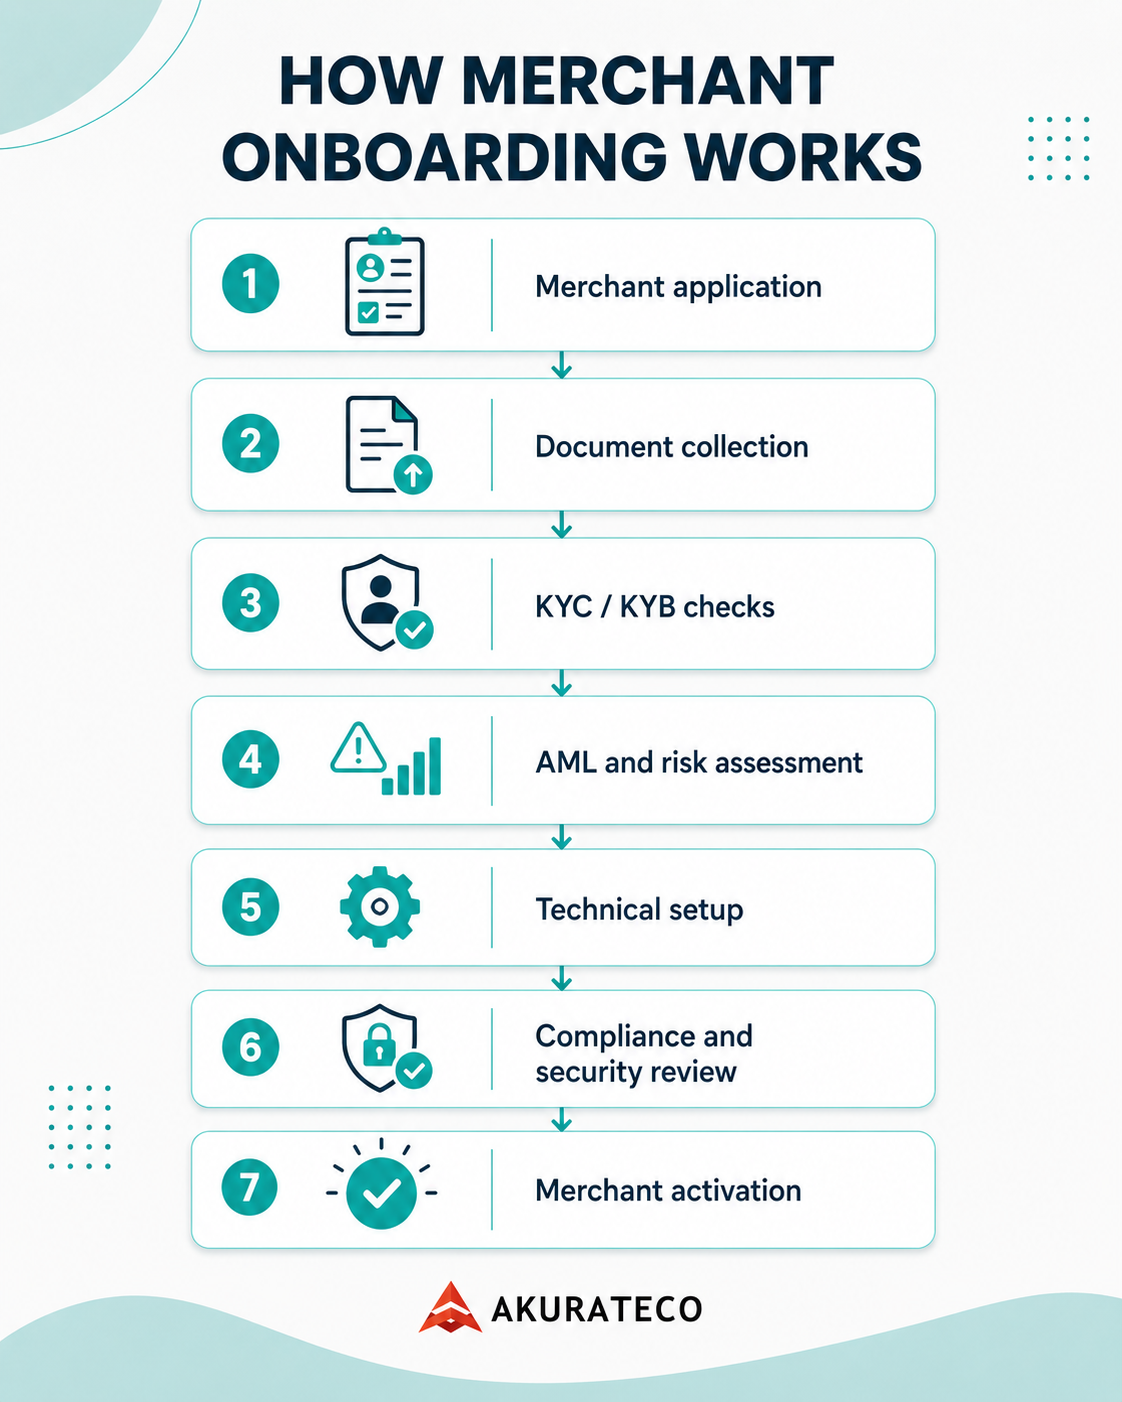
Step-by-step: How merchant onboarding works
The merchant onboarding process may vary by region, provider, business model, and risk level. However, most payment providers follow a similar workflow.
Step 1. Merchant application
The merchant submits an application with basic business information, including company name, registration details, website, business model, expected transaction volume, and payment processing needs.
Step 2. Document collection
The provider collects the documents required to verify the merchant. These may include business registration documents, proof of identity, proof of address, bank account details, ownership information, financial statements, and previous processing history.
Step 3. KYC and KYB verification
The provider verifies the identity of business owners and checks whether the company is legally registered and legitimate. KYC focuses on the people behind the business, while KYB focuses on the business itself.
Step 4. AML and sanctions screening
The merchant, beneficial owners, and related entities may be checked against anti-money laundering, sanctions, politically exposed persons, and adverse media databases.
Step 5. Risk assessment
The provider evaluates the merchant’s risk level based on industry, geography, transaction volume, chargeback history, business model, products or services, and expected payment behavior.
Step 6. Technical setup
The merchant receives the required payment setup, which may include API credentials, hosted payment page access, plugin configuration, test environment access, or other integration options.
Step 7. Compliance and security review
The provider checks whether the merchant meets relevant compliance and security requirements. For online card payments, this may include PCI DSS-related checks, website review, checkout security, refund policies, and terms and conditions.
Step 8. Approval and activation
Once verification, risk review, technical setup, and compliance checks are complete, the merchant account is approved and activated. The merchant can then start accepting payments.
What documents are required for merchant onboarding?
Asking merchants for the full set of documents up front saves time on both sides.
Providers typically request the following:
- Business license – proves that the business is legally registered.
- Tax Identification Number (TIN) – for tax purposes.
- Bank account information – connects the merchant’s bank account to the payment processing system.
- Proof of identity – a government-issued identification document (ID) of the business owner.
- Proof of address – utility bills or other documents showing the business’s physical address.
- Financial statements – recent bank statements or financial records confirming business financial health.
- Ownership information – details about business ownership.
- Payment processing history – if the merchant is switching providers, previous payment processing statements may be required.
- Compliance certificate – any relevant compliance certifications, such as PCI DSS (if necessary).
You might also like:
Compliance and fraud prevention in merchant onboarding
One of the main goals of onboarding is to confirm that a new merchant is legitimate and safe to process payments for, so compliance with security standards and regulations is central to it. In addition to PCI DSS compliance, providers must also meet KYC and KYB requirements.
Let’s explore KYC and KYB requirements in detail.
Know Your Customer
Know Your Customer (KYC) is the process of verifying a customer’s identity. It is used by payment service providers (PSPs), acquirers, banks, and other financial institutions. The main purpose of KYC is to prevent financial crime, including fraud, money laundering, and terrorist financing. In merchant onboarding, KYC covers the people behind the merchant, such as owners and directors. Based on the results, the merchant’s application is either approved or declined, and the check is repeated regularly after onboarding, not only at the start.
Know Your Business
Know Your Business (KYB) applies the same principle to the company itself. It protects payment providers and financial institutions from merchant-initiated fraud. As part of KYB, they confirm that the merchant is a legitimate, registered company, check its licenses and the identities of its stakeholders, and verify its compliance with anti-money laundering legislation.
A basic KYC/KYB review usually includes:
- Verifying the legal business name and registration number.
- Checking the company’s country of incorporation and operating address.
- Identifying directors, shareholders, and ultimate beneficial owners.
- Collecting proof of identity and proof of address for relevant individuals.
- Reviewing the merchant’s website, products, services, pricing, refund policy, and terms and conditions.
- Screening the business and related individuals against AML, sanctions, and high-risk databases.
- Assessing the merchant’s industry, geography, transaction volume, and chargeback risk.
- Deciding whether the merchant can be approved, rejected, or sent for enhanced due diligence.
After conducting the necessary due diligence, payment providers and financial institutions can assess the risks associated with a particular merchant and make an informed decision.
How Akurateco Supports Merchant Onboarding
Akurateco helps PSPs and acquirers manage merchant onboarding as part of a broader gateway solution for PSPs. Instead of handling every application manually, teams can centralize merchant data, documents, verification steps, and approval workflows in one system.
Akurateco is not a payment processor and does not process transactions itself; clients bring their own acquiring.
To learn more about Akurateco’s product capabilities for merchant management and onboarding, visit the product page.
FAQ
What is merchant onboarding?
Merchant onboarding is the procedure through which PSPs, acquirers, banks, and other financial institutions verify merchants and set them up to accept payments.
What is the purpose of merchant onboarding?
Merchant onboarding lets a payment provider verify that a merchant is legitimate and secure before partnering with it. Without it, the provider cannot activate the merchant in its system, and the merchant cannot accept payments for goods and services.
What are KYC and KYB, and their roles in merchant onboarding?
Know Your Customer (KYC) verifies the identities of the people behind the merchant. Know Your Business (KYB) confirms the company’s legitimacy and compliance with regulations. Together, KYC and KYB help prevent fraud, money laundering, and other illicit activities.
Do merchant onboarding processes differ for high-risk and low-risk merchants?
Yes. High-risk merchants typically face more rigorous examinations. This may include additional documentation and enhanced due diligence checks to mitigate potential risks. Low-risk merchants usually face a simpler, faster onboarding process with fewer requirements.
How long does the merchant onboarding take?
The merchant onboarding process duration varies from one payment solution provider to another. Typically, it takes from a few days to a couple of weeks. The exact time depends on whether the onboarding is handled manually or automatically, the complexity of the merchant’s business, and the thoroughness of the verification checks.
How to streamline merchant onboarding?
To streamline merchant onboarding, PSPs and acquirers can use payment software that automates it. Merchants then fill in forms and upload documents on their own schedule, and the provider’s team reviews the submitted data.
What should PSPs look for in merchant onboarding software?
Look for self-service application forms and document upload, forms that adapt to the merchant’s country, business model and risk profile, a single record for each merchant’s data and documents, status notifications for the team, and verification steps and approval workflows kept in the same system.