- What Is a Multi-PSP Strategy?
- Why Enterprise Merchants Move Beyond One PSP
- Multi-PSP Management vs Payment Orchestration
- How Multi-Acquirer Routing Works
- Declines, Cascading and Failover
- Cutting Costs and Raising Approval Rates by Market
- Direct Integrations, In-House Switch or Orchestration Platform
- When a Multi-PSP Setup Pays Off
- How to Implement a Multi-PSP Strategy
- Common Mistakes With Multiple PSPs and Acquirers
- How Akurateco Supports Multi-PSP and Multi-Acquirer Setups
- Conclusion
Many merchants still rely on a single payment service provider (PSP) because it seems simpler to manage. That approach comes at a price: higher blended transaction fees, poor regional approval rates, and zero fallback when things go wrong.
Working with several PSPs and acquirers gives enterprise merchants more payment coverage, greater resilience, and more flexibility in how transactions are processed. It can also create a fragmented setup in which every provider has its own API, transaction statuses, decline codes, reporting format and settlement schedule.
A multi-PSP strategy routes each transaction to the provider best suited to it under defined rules, instead of sending everything to one PSP. An orchestration layer makes those connections work as one payment stack: it selects the route, handles recoverable failures and records every result in a standard format.
What Is a Multi-PSP Strategy?
A multi-PSP strategy is a way of processing payments in which an enterprise merchant connects to more than one PSP or acquirer and routes each transaction between them by rules: country, currency, card type, cost or provider performance. The goal is a lower cost per successful payment, higher approval rates and no single point of failure.
Multi-acquirer payment orchestration is the centralized routing and management of transactions across two or more acquirers. It combines provider connectivity with routing rules, cascading, failover, transaction monitoring, and reconciliation.
In practice, the merchant integrates once with the orchestration layer instead of building and maintaining a separate integration with each provider.
PSPs, Acquirers and the Orchestration Layer
A PSP handles payment processing on the merchant’s behalf and often bundles gateway, acquiring and payment method access. An acquirer is the bank or licensed institution that accepts card payments on the merchant’s behalf and settles the funds to the merchant’s account. The orchestration layer sits above both: it does not process payments itself but decides which PSP or acquirer receives each transaction. A setup that can work with whichever acquirers the merchant chooses is called acquirer-agnostic.
Single-Acquirer vs Multi-Acquirer Setup
In a single-acquirer setup, most transactions follow one predefined processing path. The merchant depends on that provider’s geographical coverage, availability, payment methods, authorization performance, pricing structure, and reporting capabilities.
A multi-acquirer setup introduces alternative routes. For example, one acquirer may be used for domestic card payments, another for cross-border transactions, and a third as a backup during technical incidents.
Why Enterprise Merchants Move Beyond One PSP
Payment teams at enterprise merchants now manage:
- Multiple markets, each with unique regulations and payment preferences
- Blended transaction fees that vary widely depending on method, geography, and volume
- PSPs with fluctuating uptime, approval rates, and settlement terms
And yet, many still route 100% of their transactions through a single provider. The result is missed savings, lost sales, and a weak position in negotiations. Reliance on one PSP also limits the ability to test and optimize transaction flows based on real performance data.
Adding providers helps only when each transaction is routed by rules and data. Stacking PSPs without that logic adds cost and complexity without improving results.
What a Multi-PSP Setup Changes
- Cost Optimization: Payments go to the lowest-cost provider that still approves them.
- Improved Resilience: If one provider fails, payments switch to a backup PSP instead of being lost.
- Higher Approval Rates: Routing by country or card BIN sends payments to the providers that perform best in that market.
- Greater Flexibility: Providers can be added or switched without rebuilding the checkout.
- Stronger Negotiating Position: Benchmarks across providers create price competition between them.
Why Adding Providers Is Not Enough on Its Own
Several PSP or acquirer integrations provide more processing options, but orchestration determines how and when those options are used. Every acquirer may use different:
- API structures and authentication methods
- Payment statuses, decline codes and error codes
- Reporting formats and settlement files
- Supported currencies and payment methods
- Capture and refund processes
- Recurring payment requirements
When these integrations are managed independently, adding a new acquirer becomes another engineering project. Routing rules may be hard-coded into the merchant’s backend, and changing traffic allocation may require development work and a new release.
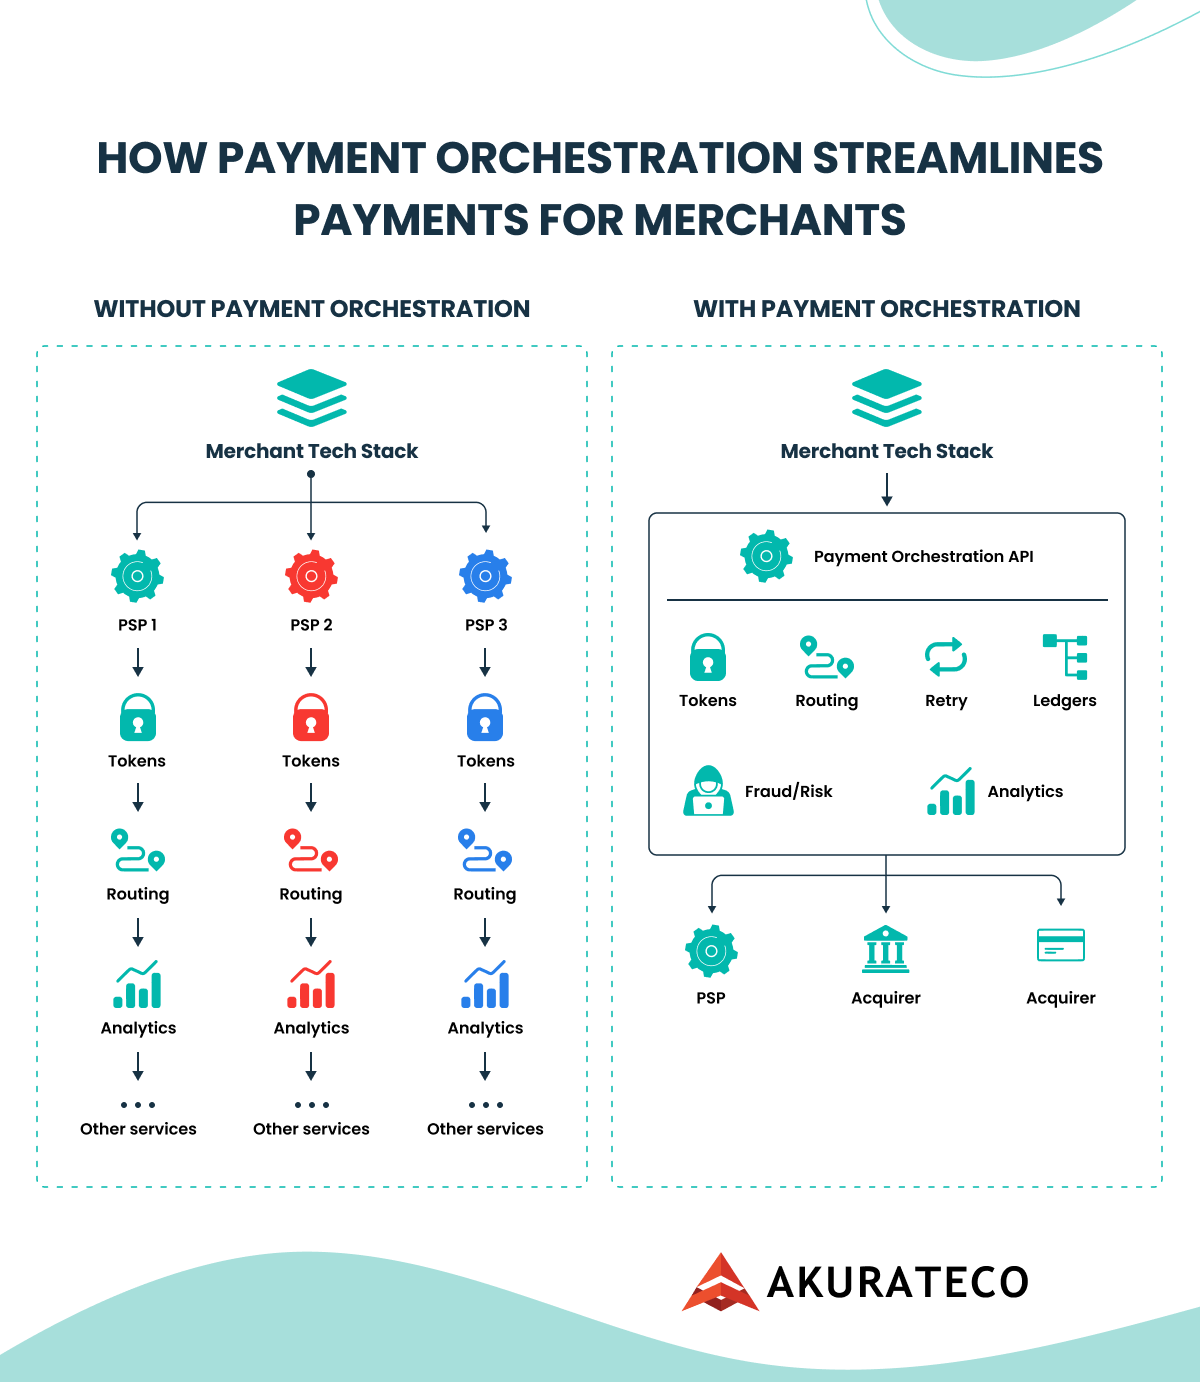
A payment orchestration platform centralizes these processes. The merchant sends a standardized payment request to one infrastructure layer, while the platform manages the differences between individual acquirers.
This makes it possible to change routing rules, introduce backup routes, add payment providers, and compare performance without rebuilding the entire checkout infrastructure.
“Too many companies see PSP setup as a one-time decision. In reality, it should evolve with your business. A multi-PSP strategy gives you the flexibility to adapt. We’ve seen merchants gain hundreds of thousands in recovered revenue simply by rerouting transactions to better-performing providers.” – Volodymyr Kuiantsev, Co-Founder and CEO at Akurateco
Multi-PSP Management vs Payment Orchestration
There are two ways to run several providers. The merchant’s own team can manage separate direct integrations, each with its own dashboard, reports and logic. Or an orchestration layer can sit above all providers and manage them through one API. For a full walkthrough of the second model, see how the orchestration layer handles providers, routing and payment flows.
| Feature | Multi-PSP management | Payment orchestration |
|---|---|---|
| Connects to multiple PSPs | Yes, each one separately | Yes, through one layer |
| Integration type | Separate integration for each PSP | One API for all connected providers |
| Dashboard | One per provider | One centralized dashboard |
| Routing | Only if the merchant builds it | Configurable rules |
| Monitoring and reporting | Manual, fragmented | Automated, unified |
| Adding a provider | A new integration project each time | Added through the orchestration layer |
| Approval rate impact | Possible through manual traffic allocation, no automatic rerouting | Rule-based routing and cascading |
| Compliance scope | Handled per PSP | Managed within the orchestration layer |
What Changes for Payment, Engineering and Finance Teams
- Engineering: One integration replaces separate work for each provider, and switching providers no longer means a new build.
- Payment operations: New payment methods and providers are rolled out and tested faster, because the connection already exists.
- Finance: Transaction and settlement data from all providers sits in one dataset, so matching transactions against settlements no longer depends on a spreadsheet per provider.
- QA: Standard statuses, error codes and checkout flows reduce the testing needed for each provider.
How Multi-Acquirer Routing Works
A typical flow runs from payment initiation to post-payment reporting. The exact sequence depends on the payment method, merchant configuration, authentication requirements, and risk strategy. From the checkout’s point of view, the orchestration layer acts as one payment gateway with multi-PSP routing behind it.
| Stage | What happens | Main systems involved |
|---|---|---|
| Payment initiation | The customer confirms the purchase | Checkout and merchant backend |
| Request normalization | Payment data is converted into a standard internal format | Merchant API and orchestration layer |
| Eligibility filtering | Unsupported or unavailable routes are excluded | Routing engine and provider configuration |
| Risk and authentication | Fraud rules and 3D Secure are applied where required | Fraud tools, 3DS provider, orchestration platform |
| Acquirer selection | The primary processing route is chosen | Smart routing engine |
| Authorization | The payment is submitted to the acquirer and issuer | Acquirer, card network, issuing bank |
| Response evaluation | The result is classified and normalized | Orchestration platform |
| Cascading or failover | An eligible transaction is redirected when necessary | Routing engine and alternative acquirer |
| Post-payment operations | The transaction is captured, monitored, reported, and reconciled | Payment operations and finance systems |
Before choosing a route, the platform converts the merchant’s request into a standard format and removes providers that cannot process the transaction, for example because they do not support the currency, card scheme, recurring model or 3D Secure flow. An acquirer may have strong approval performance for domestic Visa transactions and still be excluded if it cannot handle the required currency.
The routing engine then picks the primary route from the remaining providers by issuer country, currency, card BIN, amount, historical approval rate, response time, processing cost or contractual traffic commitments. Any backup route must accept the same authentication data, so fraud checks and 3D Secure are planned together with routing. For the full set of rules and how they combine, see Akurateco’s guide to routing rules.
The lowest-cost route is not always the most commercially efficient route. If a provider charges less but approves fewer transactions, the merchant may lose more revenue than it saves in processing fees.
Declines, Cascading and Failover
Not every failed payment should be sent to another acquirer. Hard declines, such as a blocked card or a closed account, should not be retried. Soft declines and technical errors, such as provider timeouts, may be recovered through another route. A timeout does not always mean the authorization failed, so the platform must confirm the transaction state first: without idempotency controls and status checks, the merchant could send a second authorization for a payment the first provider already approved.
Payment cascading redirects an eligible unsuccessful transaction to another provider that supports the same currency, payment method and authentication model. It is a recovery mechanism with retry limits, not a way to retry every decline, and a strong initial routing strategy reduces how often it is needed. For a step-by-step view, see how rerouting after a decline works.
Failover handles provider outages. Even the best-performing PSPs go down, whether due to technical issues, regional outages, or provider-side maintenance. With failover in place, transactions are rerouted to a backup PSP in real time when the primary provider fails, with no manual intervention and no extra step for the customer.
For example, a company operating in LATAM faced a 2-hour outage at a local acquirer. Its transactions were redirected to a backup PSP, and it avoided nearly $50K in lost revenue.
| Mechanism | When it happens | Typical trigger | Main purpose |
|---|---|---|---|
| Smart routing | Before authorization | Transaction and provider data | Select the most suitable initial route |
| Cascading | After an unsuccessful attempt | Recoverable decline or provider response | Recover a potentially payable transaction |
| Failover | During provider disruption | Timeout, outage, or technical unavailability | Maintain payment continuity |
| Load balancing | Before authorization | Traffic or capacity policy | Distribute transaction volume |
For example, a routing rule may send a French-issued card to a local acquirer because it has historically performed well for that segment. If the acquirer returns a recoverable decline, cascading may send the transaction to a second eligible route. If the first provider is completely unavailable, failover may bypass it before or during the authorization attempt.
Cutting Costs and Raising Approval Rates by Market
To compare PSP fees and cut processing costs, merchants benchmark every connected provider on the same metrics and route each transaction to the cheapest provider that still approves it. Transaction costs vary widely depending on the provider, region, and payment method, yet a static setup sends every payment to one PSP regardless.
At Akurateco, we’ve helped clients cut processing fees by up to 15% without disrupting operations or changing payment methods.
Akurateco benchmarks every connected PSP on key metrics like:
- Transaction success rate
- Average processing fee
- Approval rate by card BIN and region
- Downtime and retry patterns
Payment teams then build routing rules such as:
- Route EU Visa cards to the lowest-fee acquirer with >95% success
- Route by fee in high-volume markets like Germany or France
- Set fallback rules to avoid retries with high-cost providers
- Switch to lower-cost PSPs automatically when fee thresholds are exceeded
The number to compare is cost per successful transaction, not the headline fee. Tracking it by provider, country and card BIN in one analytics view shows where margin is lost and gives payment teams a stronger position to renegotiate PSP contracts. For the payback side of the decision, see what an orchestration layer returns and how fast.
For example, one Akurateco client selling digital goods across Europe was paying a flat 2.9% on every transaction. After moving to dynamic routing with local PSPs in Germany, Italy, and the Netherlands, it brought its average fee down to 2.1%, which saved over $280,000 a year.
Regional Routing: Local Acquirers and Payment Methods
Payment behavior differs by region. In Brazil, many customers prefer boleto bancário; in Saudi Arabia, mada is essential; in the EU, success rates vary with the local acquirer. Routing by card BIN and country sends each payment to the local acquirer or method that performs best in that market.
For example, a SaaS platform operating in the Middle East and Europe saw a 7% drop in approval rates on mada cards in KSA. Its single PSP had low local coverage and no direct connection to mada. With Akurateco, it added a regional provider with mada support and routed Saudi transactions by BIN, which raised approval rates by 12%.
“Even small changes in how you route transactions – like switching providers for a specific BIN or country – can lead to big improvements in approval rates. That’s why flexibility and data-driven logic are critical in global payment setups.” – Andrew Riabchuk, Founder and CTO at Akurateco
Direct Integrations, In-House Switch or Orchestration Platform
Direct integrations may work for a small and stable provider setup. An in-house routing layer provides control but creates long-term development obligations, while a payment orchestration platform provides a ready-made management layer.
| Approach | Advantages | Limitations | Best suited to |
|---|---|---|---|
| Single PSP | Simple to operate | High dependency on one provider, limited fallback | Low-complexity payment operations |
| Direct integrations | Direct provider control and no additional platform layer | Separate maintenance, reporting, and routing logic | Merchants with very few stable providers |
| In-house payment switch | Custom routing and complete infrastructure ownership | High development and maintenance requirements | Large merchants treating payments as a core internal product |
| Payment orchestration platform | Centralized integrations, routing, failover, monitoring, and reporting | Requires platform evaluation and implementation | Enterprise merchants scaling across providers and markets |
With an in-house switch, the merchant owns every acquirer integration, API update, certification, retry rule and reconciliation dataset, and keeping that logic current costs more than building the first integration.
When evaluating a platform for multiple acquirers, check three things first: how deep the routing rules go, how precisely cascading can be controlled, and whether provider responses and statuses are normalized. The full checklist for enterprise evaluation teams covers the rest.
When a Multi-PSP Setup Pays Off
A merchant with a few stable providers in one or two markets can often manage them directly: separate integrations still give redundancy and some regional coverage. The case for an orchestration layer grows when volume spreads across countries and currencies, providers are added regularly, routing changes need a new release, and reconciliation depends on exports from several portals.
Typical cases:
- International e-commerce: Local acquirers for domestic payments and other providers for cross-border traffic.
- Subscription merchants: Alternative routes for eligible renewals the primary provider cannot process.
- Travel: High-value, cross-border payments where acquirer performance varies by issuer and currency.
- Marketplaces: Separate acquiring relationships per legal entity or currency, managed from one layer.
- Large retailers and digital platforms: Less dependency on one provider and backup capacity when volume peaks.
How to Implement a Multi-PSP Strategy
Implementation should begin with clear payment objectives and existing transaction data. Your current PSP stays in place while others are added, so the rollout does not disrupt live payments.
1. Establish a Performance Baseline
Measure the current approval rate, decline distribution, provider latency, technical error rate, processing cost and reconciliation workload. Without a baseline, there is no way to tell whether the new setup improves the payment operation.
2. Define the Primary Objective
Start with one clear priority: reducing dependency on one acquirer, improving payment continuity, expanding into a new market, increasing authorization performance or centralizing payment reporting. Trying to optimize every KPI at once makes the routing model difficult to evaluate.
3. Map Provider Capabilities
Document which acquirers support each country, currency, payment method, card scheme, authentication flow, refund operation and recurring payment scenario. This information forms the basis of route eligibility.
4. Connect Providers Gradually
Begin with the current primary provider, then add an alternative route for a specific market, payment method or backup scenario. Gradual implementation makes it easier to compare results and isolate operational issues.
5. Define Routing and Retry Policies
Document primary route rules, provider exclusions, traffic allocation, failover conditions, cascade order, eligible decline categories, maximum retry count, and handling of timeouts and unknown statuses. These policies should be controlled and auditable.
6. Monitor and Refine
Compare performance with the original baseline and change one routing variable at a time. Payment operations, engineering, finance, fraud and compliance teams should agree on ownership, because routing changes affect costs, reporting, settlements and customer support as well as approval rates.
Common Mistakes With Multiple PSPs and Acquirers
- Adding acquirers without a specific purpose: Every new provider adds configuration, reporting, commercial and operational work. Each acquirer should serve a defined market, performance, cost or resilience objective.
- Routing only by processing cost: A lower provider fee does not necessarily produce a lower cost per successful transaction.
- Retrying every decline: Uncontrolled retries create additional fees, duplicate-payment risk and a poor customer experience.
- Ignoring authentication compatibility: The alternative provider must be able to process the authentication result produced earlier in the flow.
- Optimizing approvals but ignoring reconciliation: A routing change can raise approval rates while adding financial complexity.
- Using one global provider ranking: Acquirer performance varies across countries, issuers, currencies, payment methods and transaction types.
- Leaving routing changes to developers only: If the payment team cannot adjust rules directly, every optimization waits for a release.
- Entering a market before checking coverage: Confirm local acquiring and payment method support before launch, not after.
How Akurateco Supports Multi-PSP and Multi-Acquirer Setups
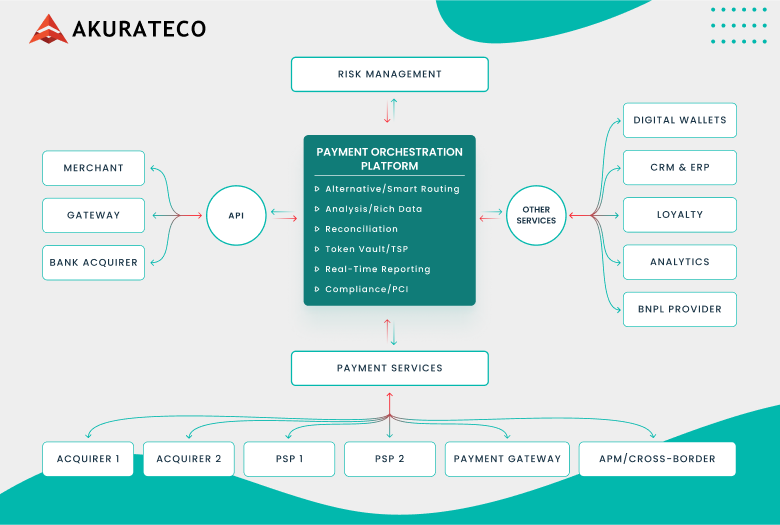
Akurateco provides the gateway and orchestration layer on top of PSPs and acquirers and does not process transactions itself. Merchants keep their own provider contracts and connect them through one API, with access to 700+ integrations.
From one dashboard, payment teams manage routing rules, cascading, transaction monitoring and reporting across all connected providers. Transactions can also be reconciled against each acquirer’s own reconciliation files. If a provider is not yet connected, a custom integration can be built on request.
To see how the platform fits your payment stack, visit Akurateco’s product overview.
Conclusion
A single PSP is simple to run, but it leaves costs, approval rates and uptime in one provider’s hands. Several PSPs and acquirers add options; an orchestration layer turns those options into one managed payment stack with clear routing rules, controlled retries and one dataset for finance. It works best as an ongoing operating model: measure, adjust, and add providers as markets change.
Multi-PSP Strategy FAQ
What is the difference between a multi-PSP setup and a payment orchestration platform?
In a multi-PSP setup without orchestration, the merchant integrates and manages each PSP separately, with its own dashboard, reports and logic. A payment orchestration platform sits above several PSPs and acquirers, connects them through one API and decides where each payment goes using routing rules, cascading and failover, with all transaction data in one place.
Can I keep my current PSP and still add others?
Yes. Akurateco supports adding PSPs and acquirers without replacing your current provider, and your existing contracts stay in place. Most merchants keep the primary PSP for its current traffic, add a second provider for one market, payment method or backup scenario, and then extend routing once the first results are measured.
How do I compare PSP and acquirer performance over time?
Track each provider by transaction segment rather than one overall figure: approval rate by country and card BIN, technical error and timeout rates, response time, cascading recovery rate and cost per successful transaction. Akurateco’s benchmarking tools show these metrics across all connected providers, so payment teams can compare them side by side and adjust routes.
Should every declined payment be retried with another acquirer?
No. Only eligible failures should be cascaded to another acquirer, such as soft declines and technical errors like timeouts. Hard declines, such as a blocked card or a closed account, should not be retried, and uncertain results need a status check first so the customer is not charged twice. A retry policy with limits and decline categories keeps fees and duplicate-payment risk under control.
How long does it take to implement a multi-PSP strategy?
Many merchants are fully operational within weeks. The timeline depends on how many PSPs are involved, the complexity of the existing payment setup and the routing features you plan to use. Starting with one additional provider for one market or backup scenario shortens the first phase, and more routes can be added once the first results are measured.
Is multi-acquirer routing only for large enterprises?
It brings the most value to mid-size and large merchants that process high volumes across several markets, currencies or payment methods. A merchant with one or two stable providers in a single market can often manage them directly. The case for orchestration grows as the number of providers, countries and reconciliation tasks grows.
How does payment orchestration affect PCI DSS and PSD2 compliance?
An orchestration layer can take card data handling off the merchant’s own systems through tokenization, which reduces the merchant’s PCI DSS scope, and it supports the 3D Secure flows that PSD2 strong customer authentication requires. The merchant still owns its own compliance obligations, so check the platform’s certifications during evaluation.
Can I manage multiple PSPs and acquirers from one Akurateco dashboard?
Yes. Akurateco gives payment teams one dashboard for routing rules, cascading, transaction monitoring and reporting across all connected PSPs and acquirers. Providers are connected through one API, so adding or switching a provider does not require a new integration on the merchant’s side. Akurateco does not process transactions itself, and your existing provider contracts stay in place.