- What is payment processing?
- Who is involved in payment processing?
- What is a payment processor, and what does it do?
- How payment processing works, step by step
- Authorization, clearing and settlement compared
- How online payment processing differs
- How to choose a payment processor
- Where Akurateco fits
- Conclusion
Payment processing is the process of collecting, verifying, and transmitting payment information from customers in order for the merchant to receive a payment. For merchants, how this flow is set up affects their approval rate, the cost of each transaction, and how quickly funds reach their account.
Below, we explain how payment processing works from checkout to the merchant’s account. You’ll learn who takes part, what happens at each step, what a payment processor does, and how to choose one.
What is payment processing?
Payment processing is what happens between a customer paying and the merchant receiving the money. The payment details travel from the checkout to the bank that issued the card. That bank checks the card number, expiry date, CVV, and often the billing address, then approves or declines the charge. If it’s approved, the funds are later settled to the merchant’s account.
The same flow runs whether a customer orders from an e-commerce store or buys movie tickets. Along the way, several parties handle the payment, each responsible for one part of the flow.
Who is involved in payment processing?
The main parties in a payment processing system are the customer, the merchant, the payment gateway, the payment processor, the card network, the issuing bank, and the acquiring bank. Each one handles one part of the flow, from capturing card data at checkout to approving the payment and moving the funds. One company can perform several of these roles: an acquiring bank, for example, may also act as the processor.
The customer and the merchant
The customer, or cardholder, starts the payment by entering card details or choosing a wallet at checkout. The merchant sells the goods or services and accepts the payment through its checkout, which connects to the rest of the chain through a payment gateway. To receive card payments, the merchant needs a merchant account with an acquiring bank, either directly or through a payment service provider. A payment aggregator is another route: its merchants accept payments under the aggregator’s account instead.
Payment gateway
A payment gateway is software that captures the customer’s payment data at checkout, encrypts it, and sends it to the processor or acquiring bank. When the response comes back, the gateway passes it to the merchant’s checkout.
Many gateways also add tools such as tokenization, fraud screening, and transaction routing that improve security, help raise the conversion rate, and can lower processing costs. Our guide explains how a payment gateway handles its part of the flow in more detail.
Payment processor
A payment processor is the technical link between the merchant’s side of the payment and the card networks, handling the messages that move each transaction forward. The next section explains what a processor does.
Card network
A card network, such as Visa or Mastercard, connects acquiring banks with issuing banks. It routes authorization requests and responses between them, sets the rules both sides must follow, and runs clearing and settlement between its members. Some networks, such as American Express, work as three-party (closed-loop) networks and often act as the issuer and the acquirer as well.
Issuing bank (the customer’s bank)
A customer’s bank is an issuing bank that authorizes or denies a payment based on various parameters, such as the amount of money in the account or signs of fraud. It is the bank that issued the customer’s card.
Acquiring bank (the merchant’s bank)
We call an acquiring bank a merchant’s bank because it accepts transactions on behalf of a merchant. Through its processor, it sends each authorization request via the card network to the issuing bank and passes the issuer’s decision back to the merchant.
During settlement, the acquirer receives the funds from the issuer and then pays them out to the merchant’s account. It also opens the merchant account and takes on the risk of that merchant’s transactions, including chargebacks.
What is a payment processor, and what does it do?
A payment processor is a company that runs the technical side of card transactions, often for the acquiring bank, connecting merchants to the card networks and, through them, to the banks on both sides of the payment. It sends authorization requests to the card networks, returns the responses to the merchant, handles the clearing and settlement files after the sale, and produces reports on every transaction.
Front-end processing is the real-time part of the job. The processor passes each authorization request from the acquirer to the card network and brings the response back while the customer is still at checkout. Back-end processing starts after approval, when the processor sends completed transactions to the card network for clearing and manages settlement so the funds move from the issuing bank to the acquiring bank.
The gateway comes before the processor. It captures the card data, encrypts it, sends it to the processor, and shows the result to the customer. From there, the processor takes over. It carries the transaction through the card network to the issuing bank and back, and later handles clearing and settlement.
The acquiring bank handles the money side of each transaction, and the processor handles the technical side. Some acquiring banks do their own processing, while others outsource it to a third-party processor.
How payment processing works, step by step
Card payment processing runs in three stages: authorization, clearing and settlement, and funding. The eight payment processing steps below show who does what at each stage.
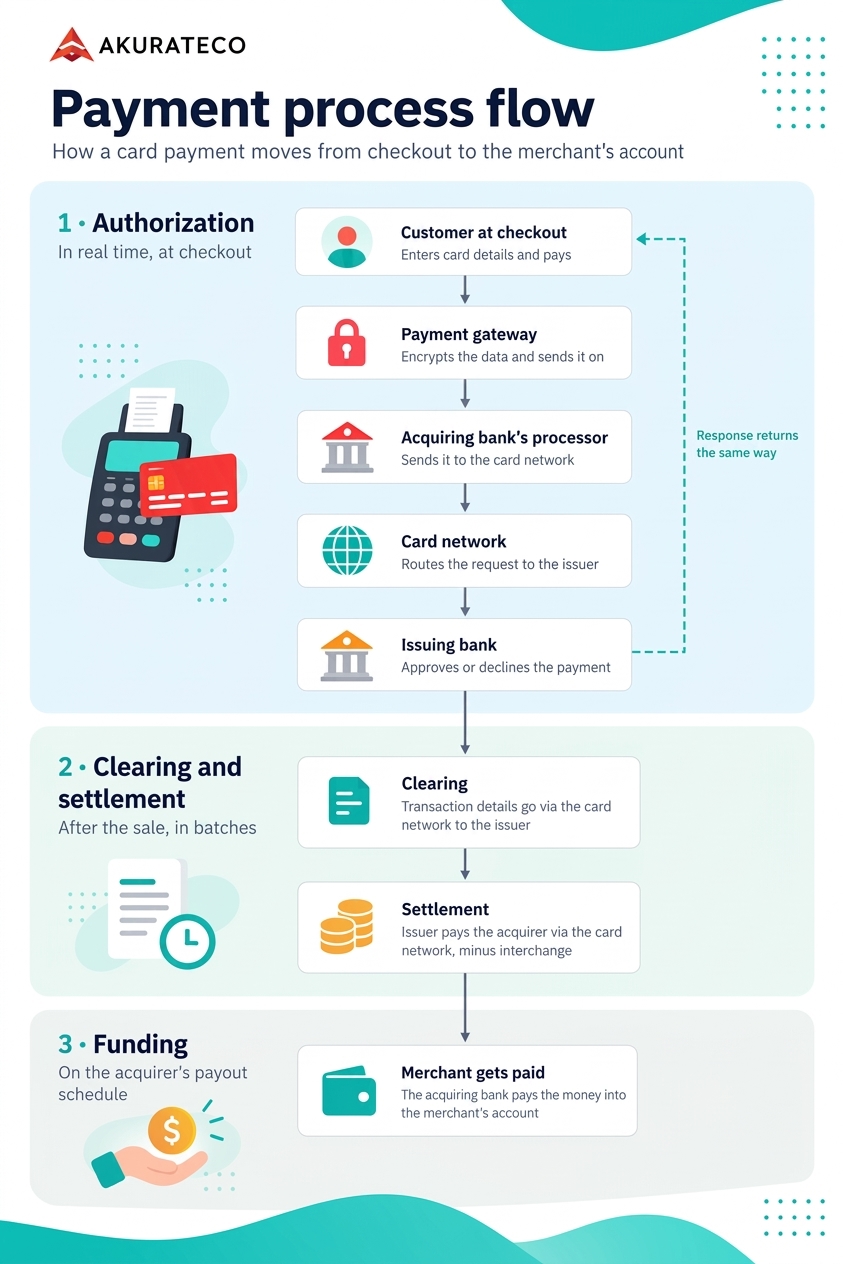
Authorization
Authorization decides whether the payment can go ahead. It happens in real time, while the customer is still at checkout.
- When the customer is ready to place an order, they choose from the suggested payment methods and enter their payment information into a merchant’s checkout page or mobile app.
- The merchant sends transaction data to the acquiring bank’s processor through a payment gateway.
- The acquiring bank’s processor submits the transaction to the card network, which transfers it to the issuing bank for authorization.
- The issuing bank evaluates the transaction and either approves or declines it.
- The authorization response is then sent back through the card network, the acquiring bank’s processor, and the payment gateway to the merchant.
Clearing and settlement
Clearing confirms the final details of each approved transaction, and settlement moves the money between the banks. Both happen after the sale and run in batches rather than in real time.
- Once the merchant captures the approved payment, at the sale or when the order ships, the transaction proceeds to clearing. The acquiring bank sends the transaction details through the card network to the issuing bank, which posts the charge to the customer’s account.
- The acquiring bank receives the relevant amount from the issuing bank through the card network, minus the interchange fee that the issuing bank keeps.
Funding the merchant
Funding is the stage at which the acquiring bank pays the merchant. How soon the money arrives depends on the payout schedule agreed between the merchant and the acquirer.
- Finally, the acquiring bank sends the money to the merchant’s account.
Merchants don’t connect to each of these parties on their own. A payment gateway or payment service provider helps them link their checkout to the rest of the chain.
Our guide to payment system architecture explains how the systems behind this flow are designed.
Authorization, clearing and settlement compared
Authorization decides whether a payment can go ahead, clearing confirms the final transaction details between the banks, and settlement moves the money from the issuing bank to the acquiring bank. Authorization happens in real time at checkout, while clearing and settlement run later, in batches, on the card networks’ daily cycles.
| Stage | What happens | Who is involved | Typical timing |
|---|---|---|---|
| Authorization | The issuing bank checks the card, the available balance or credit line, and fraud signals, then approves or declines the payment | Customer, merchant, payment gateway, acquiring bank’s processor, card network, issuing bank | In real time, usually within seconds (Visa, 2016) |
| Clearing | The acquiring bank sends the final transaction details through the card network, and the issuing bank posts the charge to the customer’s account | Acquiring bank or its processor, card network, issuing bank | After the sale, in batches |
| Settlement | The card network calculates each bank’s net position, and the issuing bank pays the acquiring bank the transaction amount minus interchange | Issuing bank, card network and its settlement bank, acquiring bank | Traditionally on business days only (Visa, 2025), though networks are now adding weekend options for some banks (Mastercard, 2026) |
How online payment processing differs
Online payment processing follows the same authorization, clearing, and settlement steps, but the card is not physically present. No chip or PIN can confirm that the card is genuine and the buyer is the cardholder. That is why these payments get extra checks. They may include authentication such as 3D Secure, where the issuing bank can ask the customer to confirm the payment in a banking app or with a one-time code, and more thorough fraud screening of signals such as the device, the billing address, and the CVV. Our guide explains how 3D Secure adds an authentication step to online card payments.
Digital wallets such as Apple Pay and Google Pay mostly store a tokenized card. These payments still run through the card networks. Wallets that hold their own balance, such as PayPal, and bank transfers work differently. The customer confirms the payment in the wallet or banking app, the money moves over the wallet’s own system or the banks’ payment rails instead of the card networks, and settlement times and refund rules follow that method rather than card scheme rules.
How to choose a payment processor
To choose a payment processor, enterprise merchants should compare four things: the technology behind it, the payment methods it supports, its full cost, and its security standards. The right choice depends on where you sell, how much volume you process, and how many acquirers you need to work with.
Technology and support
First, make sure the processor offers up-to-date technology and reliable customer support. Its technology determines how far you can grow. An outdated platform will not let you expand to new markets, connect to multiple acquirers, or reduce fraud and chargebacks.
Payment methods
Cards are only part of the mix. Check which local and alternative methods the processor supports in your target markets, such as digital wallets, bank transfers, Buy Now, Pay Later, or QR payments, and how quickly it can add new ones.
Fees
Card processing costs have three main parts: interchange, which goes to the issuing bank; scheme fees, which the card networks charge; and the processor’s or acquirer’s markup. Interchange and scheme fees are set by the card networks, so the markup and any extra charges for chargebacks, refunds, or currency conversion are what to compare. Our guide to how payment processors make money explains the full model.
Security
Any processor that stores, processes, or transmits card data must comply with PCI DSS, so ask for its current Attestation of Compliance. Check how it encrypts and tokenizes card data and which fraud tools it offers to reduce fraudulent transactions and chargebacks.
Where Akurateco fits
Many enterprise merchants and PSPs work with more than one acquirer to enter new markets, keep a backup route, and compare costs and approval rates. Akurateco’s payment orchestration platform, with 700+ integrations, lets them connect several acquirers through one platform.
Akurateco is not a payment processor and does not process transactions itself; clients bring their own acquiring.
Conclusion
Every card payment goes through authorization at checkout, clearing and settlement between the banks, and funding to the merchant’s account. The payment gateway, the processor, the card network, and the issuing and acquiring banks each handle one part of that flow, and how they are set up affects the merchant’s approval rate, costs, and payout speed.
FAQ
What does “payment processed” mean?
It usually means the issuing bank has approved the payment, and the merchant has submitted it for clearing and settlement. The money may not have reached the merchant yet, and the customer may see the charge as pending for a while. The exact meaning depends on how each provider labels payment statuses.
How long does payment processing take?
It depends on the stage. Authorization happens in real time, while the customer is at checkout. Clearing follows after the sale, in batches, and settlement traditionally runs on business days only (Visa, 2025). Funding then depends on the payout schedule in the merchant’s agreement with the acquiring bank.
What is the difference between authorization and settlement?
Authorization decides whether a payment can go ahead, and settlement moves the money. Authorization happens at checkout, when the issuing bank checks the card, the available balance or credit line, and fraud signals. Settlement comes later, after clearing, when the issuing bank pays the acquiring bank the transaction amount minus interchange through the card network.
What is end-to-end payment processing?
End-to-end payment processing is the full journey of a payment, from the moment the customer pays at checkout to the moment the money reaches the merchant’s account. It covers authorization, clearing, settlement, and funding.
Does Akurateco process payments?
No. Akurateco is not a payment processor and does not process transactions itself; clients bring their own acquiring. Akurateco provides the gateway and orchestration layer on top of acquirers. Its payment orchestration platform lets PSPs, acquiring banks, and enterprise merchants connect acquirers and payment providers through 700+ integrations, route transactions, and manage payments in one place.