- What Is Payment Routing?
- Static vs. Dynamic Payment Routing
- How Intelligent Payment Routing Works
- Smart Routing vs. Cascading vs. Failover
- The Main Benefits of Intelligent Payment Routing
- Prerouting: Routing to Alternative Payment Methods
- Common Payment Routing Parameters
- How to Set Up Payment Routing Rules
- Real-life Use Cases: How Akurateco’s Clients Benefit from Smart Payment Routing
- To sum up
- Payment routing sends each transaction to the most suitable payment provider before authorization, using predefined rules.
- Smart routing still uses rules but also checks how each provider is performing right now, so every payment goes where it’s most likely to pass at the best cost.
- Smart routing fixes three common failure points: false declines when a card goes to a provider its issuer rarely approves, high processing costs, and soft declines that another provider could still approve through cascading.
- Benefits of smart routing are better approval rates, lower processing costs, and uninterrupted payments when a provider goes down or reaches its limit.
- To implement it, assess your infrastructure, find where your payments are approved and declined, turn those patterns into rules, and adjust them as results change.
A declined payment is a sale lost at the final step. The customer selected the product, added it to the cart, and entered their card details, but the transaction still failed. Those failures drive shoppers away. In Baymard Institute’s (2025) survey of US online shoppers, one in ten who abandoned a cart for reasons other than browsing named a declined card as the cause.
Intelligent payment routing, also called smart payment routing, prevents this by automatically sending each transaction to the provider best suited to it. Routing rules evaluate the transaction’s characteristics and weigh processing costs against the likelihood of approval at the moment. For enterprise merchants, PSPs, and acquiring banks, the result is higher approval rates, lower processing costs, and a smoother checkout.
In this article, we’ll explore what payment routing is, how it works, and real-life use cases from our clients.
What Is Payment Routing?
Payment routing is a technology that automatically selects the most suitable payment provider for each transaction, thereby contributing to the company’s revenue and transaction approval rate.
With advanced routing parameters, payment routing selects a suitable provider for each transaction before the transaction is sent for authorization, taking into account internal limits on certain transaction types and amounts, blocked-country lists, and other restrictions. Routing rules check each transaction’s characteristics and send it to the provider with the best balance of processing costs and approval odds. It also enables card network optimization and supports a multi-acquirer strategy, resulting in higher approval rates, lower processing costs, and a smoother checkout.
Watch the video below to better understand what intelligent payment routing is, how it works, and what benefits it brings for businesses.
The sections below cover the three mechanisms behind this: routing, cascading, and failover.
Static vs. Dynamic Payment Routing
Payment routing can be either static (following fixed rules) or dynamic (adjusting in real time based on how providers are performing). Let’s take a closer look at each of them.
| Aspect compared | Static routing | Dynamic routing |
|---|---|---|
| Configuration | Fixed routes set up manually | Rules that use real-time provider performance data |
| Adaptability | Routes stay the same until someone changes them | Adjusts automatically as provider performance changes |
| Behavior when a provider fails | Transactions sent to that provider can be delayed or fail | Transactions are sent to the best-performing provider at the moment instead |
| Best fit | Simple setups with a few providers in one market and low volumes, or where specific transactions must always go to a specific provider | Multi-provider setups where approval rates and processing costs affect revenue and thus need continuous optimization |
What is static payment routing?
Static payment routing involves manual configuration of fixed routes. Each transaction is sent to a predetermined payment service provider based on rules such as card type, currency, or country, regardless of how that provider is currently performing. The route stays the same. If the provider experiences downtime or high latency, transactions can be delayed or fail, leading to lost sales and customer frustration. That makes it inflexible to scale.
What is dynamic payment routing?
Dynamic payment routing uses real-time performance data to automatically choose the best available provider for each transaction. It stops sending transactions to a provider that is down or underperforming, and when combined with cascading, it can retry a soft-declined transaction with another provider without the customer having to pay again. This adaptive mechanism helps increase approval rates and reduce processing costs.
Key insight: Static routing looks only at the transaction data. Dynamic routing also checks how each provider is performing at that moment, so merchants can recover payments that would otherwise be declined by a slow, offline, or underperforming provider.
How Intelligent Payment Routing Works
Smart payment routing, a type of dynamic routing, is a core part of payment orchestration, with its rules configured in the system’s admin panel. Routing evaluates transaction data, such as the BIN, currency, and amount, against these rules and reference data such as BIN databases. Based on pre-set criteria, the system automatically selects the optimal payment provider for each transaction.
Once a customer confirms payment and the transaction passes fraud screening, the multi-step smart routing engine kicks in. It identifies the most suitable MID (merchant identification number) or acquirer, factoring in cost, location, currency, payment method, transaction amount, provider availability, and more.
While routing configurations vary from client to client, the goal remains the same: to maximize approval rates, reduce processing costs, and route transactions in line with local requirements.
The diagram below shows how payment routing works step by step:
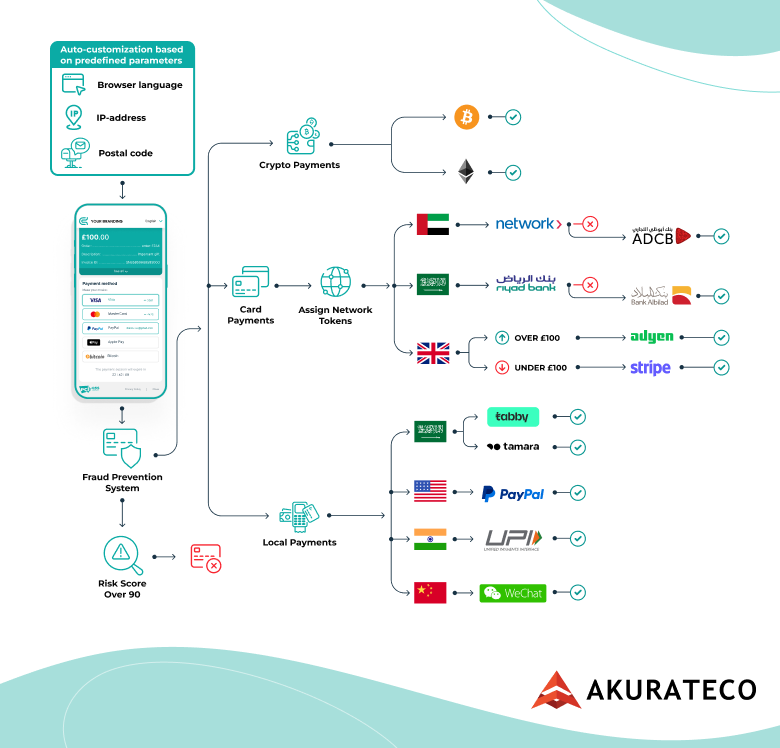
- Fraud screening. After the client confirms payment on the website or application, the automated fraud prevention system screens the payment and assigns it a risk score. If the score exceeds the configured threshold, the transaction is declined.
- Routing by payment method. If the payment passes the fraud check, the process of intelligent payment routing determines which payment providers could potentially process this transaction according to the payment method (shown in the image) or another given parameter.
- Provider selection. Based on additional parameters, such as country, transaction amount, or processing fees, payment routing identifies the most suitable payment provider to route payment to and directs the transaction there. For card payments, network tokens are assigned before the transaction is routed. For local payments, the transaction goes to the provider connected for the method the customer selected, and if several providers support that method, routing chooses among them using the same parameters.
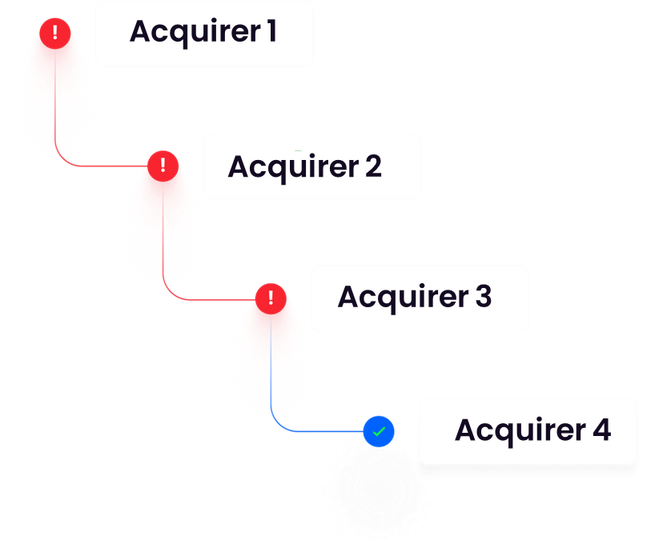
- Cascading. If a card transaction is declined (soft decline), a cascading mechanism redirects it to the next configured provider. This continues as needed, so the customer can complete the payment in a single attempt. Hard declines, such as a blocked card, are not retried.
Smart Routing vs. Cascading vs. Failover
Smart routing, cascading, and failover are related payment optimization concepts, but each solves a different problem. Smart routing decides where to send a transaction before authorization, cascading retries a transaction attempt (soft decline) through another provider, and failover keeps payments running when a provider is unavailable.
| Concept | When it applies | Primary goal | Trigger |
|---|---|---|---|
| Smart routing | Before the transaction is sent for authorization | Choose the best provider for each transaction based on approval rate, cost, geography, or other rules | A new transaction, evaluated against predefined rules or machine learning (ML) models |
| Cascading | After a soft decline | Recover that payment by retrying it through one or more alternate providers | Soft decline returned by the first provider |
| Failover | When a provider is down or degraded | Maintain payment continuity by automatically switching traffic to a backup provider | Provider unavailability, timeout, or technical failure |
Learn more about how these technologies work in Akurateco.
The Main Benefits of Intelligent Payment Routing
Akurateco’s CEO and Co-Founder, Volodymyr Kuiantsev, shares his view on the benefits of smart payment routing for enterprise merchants, as well as PSPs and acquiring banks.
Intelligent payment routing is fundamental for businesses to optimize transaction success rates and improve the user experience. It’s a revolutionary technology in the world of payments that ensures transactions are carried out efficiently and securely, regardless of any issues with individual providers. By dynamically selecting the best payment path, businesses reduce payment failures, improve risk management, and increase customer satisfaction.
Now, let’s look into the major benefits of payment routing in detail.
Lower costs without chasing the cheapest fee
Processing costs depend on card type and level, the issuer’s country, the merchant category, and whether a payment is domestic or cross-border. Card schemes set interchange, but acquirer markups vary between providers, and payment gateway routing through a local acquirer can qualify a payment for lower domestic rates.
The cheapest provider is not always the most cost-effective. Smart routing takes this into account. It uses real-time fee and approval data to weigh cost against approval probability, settlement speed, reliability, and risk, and sends each transaction where it nets the most.
Sending each payment where it’s likely to pass
Approval rates rise when each transaction goes to the provider or bank most likely to approve it. Routing rules take each connector’s limitations into account, such as payers from countries a provider does not serve or high-risk industries it doesn’t accept, and never send those transactions to that provider in the first place. Machine-driven logic and AI-enhanced analytics add to this uplift.
Uninterrupted payments across providers and MIDs
Merchants and PSPs decide how transactions flow across their MIDs and providers. They can split volume between providers, keep each MID within its processing limits, and move traffic away from a provider that is underperforming or unavailable. If one provider goes down, payments go through another. A MID that hits its limit hands traffic to the next one instead of declining it.
Prerouting: Routing to Alternative Payment Methods
Prerouting is a technology that routes transactions to MIDs based on data unrelated to credit or debit cards. It’s used for transactions made with alternative payment methods (APMs) to route them by currency, payer’s country, and other parameters. This gives users more control over transaction flows and improves overall recovery rates for failed transactions.
Card routing has something to work with from the start. The BIN tells it the card’s brand, type, and issuing country. A bank transfer or e-wallet payment doesn’t carry a BIN. Prerouting fills that gap by choosing the MID for alternative payment methods from other data, such as currency or the payer’s country.
Take a PSP connected to two APM providers in Latin America. With prerouting, BRL payments from Brazilian payers go to the provider that supports Pix, and MXN payments from Mexican payers go to the one that supports SPEI. Rules can also use other non-card parameters.
Prerouting is useful for a PSP once its merchants accept APMs in several markets through different providers. Without it, a payment can end up on a provider that doesn’t serve the payer’s country or currency and fail for a reason that has nothing to do with the payer.
A merchant needs it when entering a new market. Local methods come through a new provider, and prerouting sends that market’s traffic to the new MID while existing payments keep their current routes.
Common Payment Routing Parameters
Routing decides where a transaction goes using data it already has about the payment, the payer, the card, and the available providers. Which parameters to configure depends on the markets, payment methods, and providers a merchant or PSP works with, as well as payment routing optimization goals. Most setups combine several of them.
Geolocation of the billing address
The billing address shows where the payer says they are, which isn’t always where the card was issued. Routing rules mainly use it for risk. If the billing country doesn’t match the BIN country, the payment can go to a MID with stricter risk settings. It also helps when some providers only serve certain regions.
Payment method
This is usually the first split in a routing setup. Cards, e-wallets, and bank transfers each need a provider that supports them. The payment method narrows down which MIDs are considered at all. The methods that carry no card data go to prerouting.
Customer segment or whitelist status
Repeat buyers and whitelisted payers carry less risk than first-time traffic. Some merchants route them through a separate MID, so a fraud spike from new customers doesn’t drag down the approval rate and chargeback ratio of their most reliable traffic.
Bank identification number (BIN)
The BIN is the first six or eight digits of a card number. It identifies the issuing bank, card brand, card type, and issuing country. Issuers approve at different rates depending on the acquirer, so BIN-based routing sends each card to the provider with the best results for that issuer. It’s the most precise card parameter and works best once there’s enough approval history per issuer.
BIN country
If the acquirer is in the same country as the issuer, the transaction counts as domestic, which usually means lower interchange and fewer declines from issuers cautious about cross-border payments. That’s why the BIN is checked for the issuing country before the MID is chosen. The rule only works once a merchant has local acquiring in that market, since without a local MID there’s nothing to route to.
Card brand
Visa, Mastercard, American Express, and other networks are priced differently by each acquirer, and approval results vary too. Some acquirers don’t support every brand, which makes this a basic filter as well as a cost lever.
Currency
A provider that processes and settles in the payment’s currency spares the merchant a conversion step and the FX markup that comes with it. This parameter matters most when a merchant sells in several currencies, and its providers support different currency sets.
Transaction amount
A €15 payment and a €1,500 payment aren’t the same transaction, even on the same card. Small payments are often cheaper on a provider with a low fixed fee, while large ones benefit from a lower percentage rate, and it may also need a MID with tighter fraud controls. Recurring payments can also follow their own rules.
Provider performance and availability
This is the only parameter that changes minute to minute. The rule needs at least two MIDs that can take the same payment, so it goes in once other rules have narrowed the choice down to a few. It measures approval rates, response times, decline patterns, technical errors, and downtime over a recent window, and the condition is a threshold. If a provider’s approval rate for a segment falls below it, that provider drops out of the running. It protects approvals and uptime when a provider degrades, without anyone having to notice first.
Custom routing rules
Custom rules combine several parameters in a single decision.
Let’s say Mastercard payments on cards issued in Germany above €500 go to a German acquirer for as long as its approval rate for that segment stays above a set threshold. If the rate drops, the same payments move to a second acquirer with strong results on German cards, while smaller amounts keep their usual route.
How to Set Up Payment Routing Rules
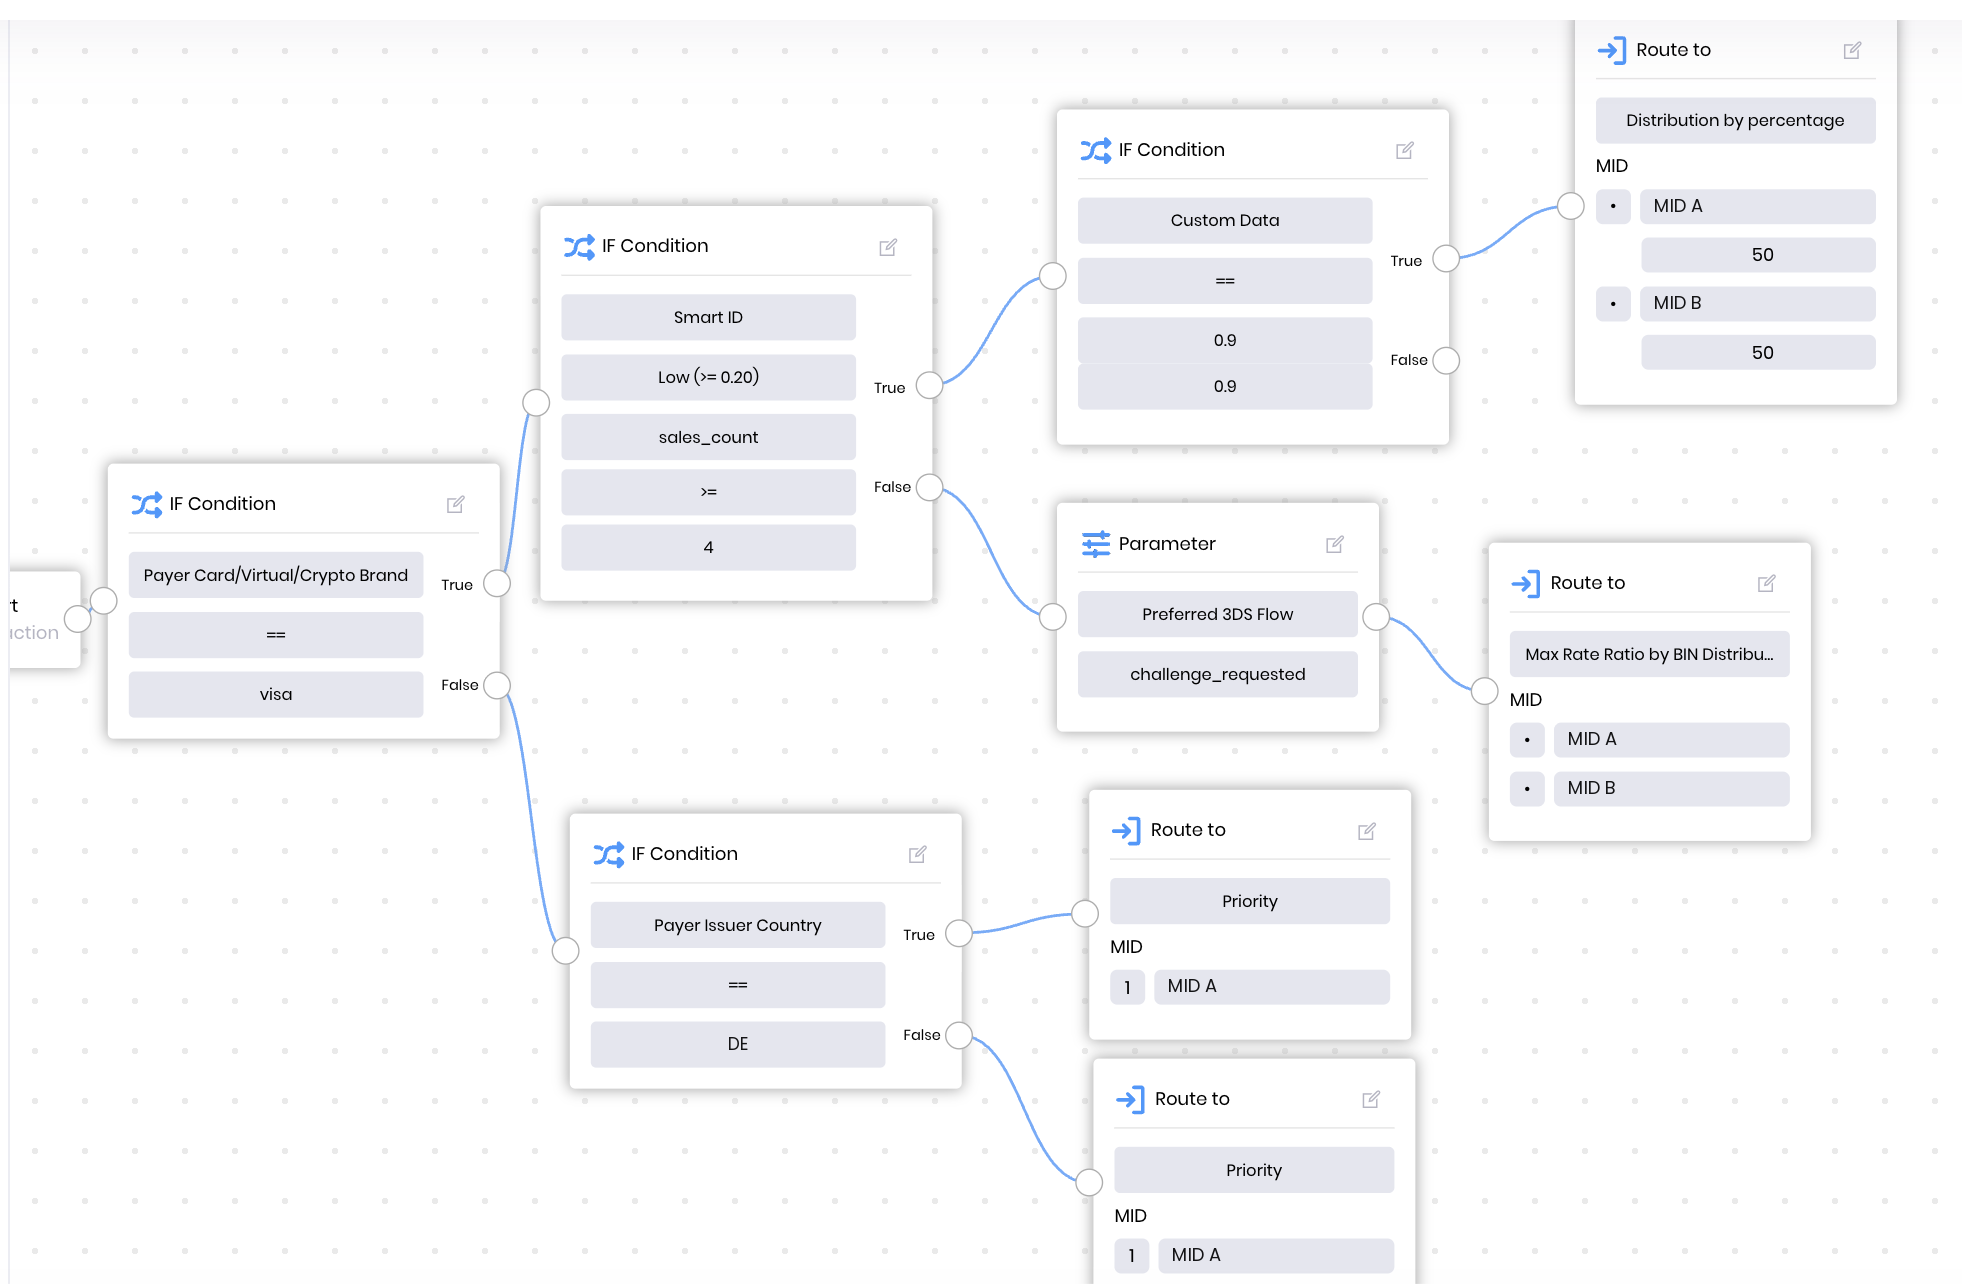
With payment routing software, you build rules around your own data: look at where transactions go and where they fail, turn those patterns into conditions, and adjust them as provider results change.
Audit current payment flows and decline points
Break down approvals and declines by provider, issuer country, card brand, payment method, and amount, and separate soft declines from hard ones. Soft declines are worth routing around, since the same payment can succeed elsewhere. Wherever one provider approves noticeably less than another on the same segment, there’s a rule waiting to be written.
Define rules
Provider performance, geography, card type, processing cost, and approval history are the usual starting points, and one rule can combine several of them.
Cost belongs here from the start. Each routing decision changes what a transaction costs. The provider sets the acquirer markup, and the acquirer’s location decides whether the payment is priced as domestic or cross-border interchange.
Test provider combinations
A rule built on past data is still a hypothesis. That’s why you send comparable traffic to each candidate provider with everything else held equal, and then compare approvals and costs on the same segment. A provider that wins on German cards may lose on Spanish ones.
Monitor and adjust
You may notice that a setup that performed well last quarter can quietly lose money now. The loss hides in the overall approval rate unless you track it per rule. A lot can change since you last updated the logic, including providers’ pricing and scheme update rules. That’s why it’s not a template. Revisit the scheme whenever a provider, market, or payment method is added.
Real-life Use Cases: How Akurateco’s Clients Benefit from Smart Payment Routing
Akurateco’s platform runs under each client’s own brand, so the names of the three clients below stay confidential. They operate in different sectors and regions.
Client A: Routing FTD and Whitelisted Traffic Separately
Challenge: A PSP serving e-commerce merchants worldwide ran its own routing system, but the system couldn’t be customized by parameter. It had no way to send first-time deposits (FTDs) and whitelisted traffic to different MIDs.
FTDs are a payer’s first transaction on a site, with no history to judge them by, so they face stricter risk checks. Whitelisted traffic comes from trusted payers with a record of successful payments. Without separate routing, trusted payers could land on an acquirer with strict risk rules, or in a region where their card looked new, and be declined as if they were unknown. The result was false declines and lost revenue for the PSP’s merchants.
Solution: Client A uploaded its merchants’ whitelists to Akurateco and connected three MIDs. Smart routing now sends whitelisted transactions to a dedicated MID and FTDs to a second one. If an FTD is declined for reasons on the MID’s side, it cascades automatically to the third MID, which also accepts FTD traffic. The PSP no longer has to maintain its own routing system.
Result:
- $150,000+ savings in system maintenance over one year
- 11% increase in approval rate
Client B: Balancing Transactions Across MIDs
Challenge: A global streaming service processed payments through two MIDs with identical processing criteria and needed to stay under its 10,000-transaction limits. Filling one MID before switching to the other risked declines and system failures, so the client wanted both MIDs processing at the same time. Velocity limits added a second constraint. They cap the number of successful transactions one customer can complete on a single MID within a set period, for example, three a day.
Solution: Akurateco added “Distribute by count” and “Distribute by percentage” modules to its routing engine. By percentage, the client can send, for example, 30% of traffic to one MID and 70% to the other. By count, traffic moves in batches: after four successful transactions on the first MID, the next two go to the second, and then traffic returns to the first. Spreading customers across both MIDs kept them within their velocity limits, and the client kept every acquirer relationship without closing any.
Result:
- No velocity limit breaches
- Optimized merchant processing capacity
- Increased number of successful daily transactions without system failures
Client C: Optimizing Local and International Traffic
Challenge: A Qatari telecom provider needed to route local and international payments to different acquirers for cost efficiency. Its acquirer charged separate interchange tariffs for local and foreign cards: local rates were low, but international ones were notably expensive.
Solution: Akurateco set up routing by BIN country. Payments on locally issued cards go to the local acquirer, while payments on cards issued abroad go to an international provider with more cost-effective cross-border interchange rates.
Result:
- 0.5% cost savings on every cross-border payment
- Optimized interchange fees across all payments
To sum up
Every declined transaction is revenue that was already in the checkout. Intelligent payment routing weighs approval probability, cost, settlement speed, and reliability for each payment in real time, and cascading retries soft declines that can still succeed elsewhere.
In practice, by using a payment routing solution with intelligent payment routing and cascading, merchants, PSPs, and acquiring banks can improve approval rates, reduce processing costs, and recover revenue that may otherwise be lost.
Payment Routing FAQs
What is payment routing?
Payment routing is the process of deciding where each transaction should be sent for processing. Rules can route it to different providers, based on geography, card type, currency, cost, risk level, or how a provider has performed on similar payments before.
What is smart payment routing?
Smart payment routing is a type of dynamic payment routing. It still uses rules like static but adjusts based on performance data or machine learning to choose the best-performing provider for each transaction. Its goal is usually to improve approval rates and control processing costs.
How does payment routing work?
Payment routing works by evaluating a transaction before it is sent for authorization. The system reads what it knows about the payment (card BIN, issuer country, currency, payment method, amount), checks it against the configured rules along with provider availability, cost, and approval history, then sends the transaction to the provider that offers the best combination of approval odds and cost.
What is transaction routing?
Transaction routing is the broader process of directing a transaction to the most suitable processing path. In payments, transaction routing often means sending each payment to the right provider, based on predefined business and performance rules.
What is approval routing in payment processing?
Approval routing sends each transaction to the provider most likely to approve it. The rules rely on historical approval data by issuer, card brand, and country, plus each provider’s current performance.
What is the difference between payment routing and payment cascading?
Routing decides where a transaction goes before it’s sent for authorization on the first attempt. Cascading occurs after the transaction has already been declined (soft decline), when the system makes a second attempt with another provider.
How do payment routing rules affect processing costs?
Each rule decides which provider gets the transaction, and that provider sets the acquirer markup. The acquirer’s location also determines whether the payment is priced as domestic or cross-border interchange. But the least-cost routing isn’t always the best, since a lower fee saves little if that provider approves fewer payments.